


So, the statistics for 2025 are in on whether the Trump Administration’s approach of “tariff everything” (which is in fact a revenue tariff not a protective tariff as per William McKinley himself) has been a success - and despite the claim that the “Golden Age” is upon us, it is looking like you are not included in those positive projections for the future.

Trump’s tariffs did generate revenue, approx. $250 billion, however, according to a study published in January 19, 2026 by the Kiel Institute für Weltwirtschaft, this money was not generated from overseas but rather 96% of this “revenue” from the tariffs came from the American consumers and producers. Foreign exporters in reaction to the Trump tariffs simply raised their prices to compensate or exported fewer products.
Let’s look at the automobile sector as an example:
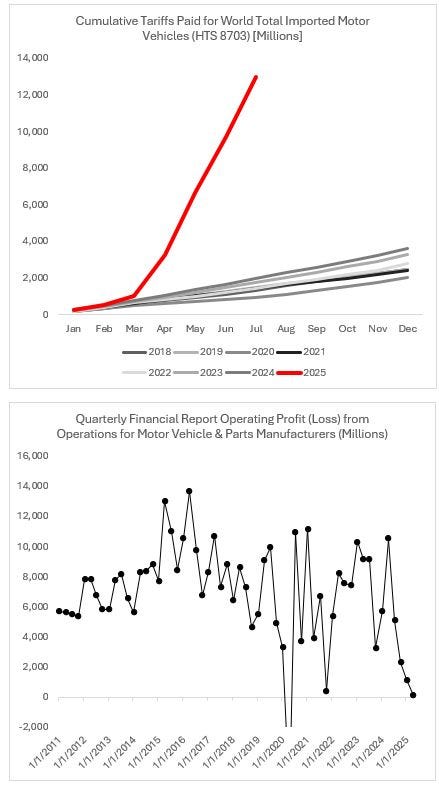
The top chart shows the cumulative duties since 2018 for imported vehicles. We can see with the red line, representing the year 2025, that the calculated duties as of July were $12.97 billion, compared with July in 2024 at a total of just $1.97 billion. This was a massive cost shock to American automobile assemblers. This shows that it was the American automobile producers who were hit hardest with the Trump tariffs, not its foreign competitors.
The bottom chart shows the operating profit (loss) from operations for motor vehicles and parts manufactures (NAICS 3363) from the Quarterly Financial Report. Q2 2025 was the second lowest profit quarter going back to 2011, with only the Q2 2020 COVID lockdown quarter being worse. [1] Firms made just $114 million in operating profit off of $229 billion in revenue or a ratio of operating profit over loss (expressed as a percentage) of just 0.05%. In other words, for every $1 of revenue, operating profit was $0.0005. [2] That is a net loss of huge proportions and is clearly not sustainable…
This reminds me of when Biden claimed a Real GDP increase of 2.8% in 2024, however, what he didn’t tell you was that that “growth” was made possible with a GDP Deficit of 6.4%. As we can appreciate with the below graph from the US Treasury Department, almost all of the United States’ so-called GDP growth from especially 2010 till today, is in fact coming from massive deficit spending. In other words, the United States is borrowing money “to keep the party going,” there is no net growth.

And in the case of the 2025 tariffs, we can see that any “revenue” claimed as a profit is being paid by the American consumer or producer
“In Q2 2024, auto assemblers built 10.7 million passenger vehicles in the USA on a seasonally adjusted annual rate. That number was 10.3 million in Q2 2025 (relatively unchanged). Yet, profits plunged to one of the lowest levels in nearly 15 years. The tariffs are to blame.” [3]
Thus, there was no actual boost to the manufacturing base of the United States from these revenue tariffs, in fact, revenue was actually taken from the American consumer and producer base to pay off debt that has been accrued over the decades from the speculative antics of Wall Street (anyone still remember that nothing changed after the 2008 financial crash???). I know ex-lieutenant of Soros, US Secretary of Treasury Scott Bessent does, where do you think he made his billions of dollars from?
To further confirm that US manufacturing in fact took a hit rather than a boost from these policies here are some statistics from the past year:
Manufacturing employment sank for 11 of the 12 months of 2025. Approx. 89,000 jobs were lost over the past year, particularly pronounced in the durable goods sector including industries like automotive and electronics.
There were 1.17 million layoffs, over 25% were federal government, the next highest was in technology, warehousing, retail services, financial, and healthcare.
Global and Domestic demand for U.S. products has declined, while demand for global manufacturing has increased. (In other words global demand increased despite U.S. demand decreasing, so, the U.S. has a decreased participation in world trade.)
Based on the Federal Reserve Bank of New York’s Household Debt and Credit Report for Q3 2025, US household debt reached a record high of $18.9 trillion an increase of $642 billion in one year. This amounts to an entire budget of a major industrialized country such as Germany. So, Americans officially got much more poor during 2025.
Since U.S. bank asset values are inflated, when the two-quadrillion-dollar global financial bubble bursts, they will turn into the largest aggregate loss in history.
There is no way to prevent this collapse of the system unless, rather ironically after Jamieson Greer’s speech at Davos, the Trump Administration truly returns to the Hamiltonian roots of the American System school of protectionism instead of using empty words.

This begins with the re-implementation of Glass-Steagall bank separation policy to remove the parasitical banking of Wall Street from the essential functions of commercial and savings banks that are tied to the real economy, such as the manufacturing/industrial sector.

With this in mind, I would like to reshare with you all Part II of my “Make Whose America Great Again?” series (with some recent updates) where I went over in detail last summer 2025 why the Trump Adminsitration’s approach to tariffs were going to gut U.S. manufacturing rather than save it and work to decrease the overall standard of living for Americans. And keep in mind here, we are only into the first year of this policy…
- Cynthia Chung, Feb, 12, 2026
US Billionaires Unite to “Make America Great Again”
By Cynthia Chung
(published May 8, 2025)
Part I discusses the story of America’s deindustrialisation, which began in the 1960s. In the following decades the United States became increasingly a services economy which included the financialization of debt, that now makes up a large portion of US revenue. Today the American economy largely consists of revenue from casino (i.e. Wall Street) and landlord profits, such as Blackstone the largest commercial landlord in the world. Blackstone made a killing off of the housing bubble bust during the 2008 financial crisis and is a big reason why Americans can no longer afford to purchase a house of their own. Part I also goes through the real reason why the reciprocal tariffs were paused only one week after they were announced.
In Part II we will do an overview of what US Treasury Secretary Scott Bessent and US Secretary of Commerce Howard Lutnick have set forth in their promise to Americans to bring back jobs, with a focus on manufacturing jobs. And to rebuild industry, especially in advanced technologies.
We will also discuss the outcome thus far in Bessent’s global tariff strategy as well as how the US tariff war is fairing in its face-off with China.
Also make sure to check out Part III of this series:
The Difference Between William McKinley’s American System School of Protective Tariffs and Today

You can read the First Instalment here (which focuses on Mathew Carey and Henry Clay as the founders of the American System of protectionism and their opposition to the British system of free trade), the Second Instalment here (which focuses on Lincoln and his advisor He…
Wall Street vs Main Street
Before we get into the nitty-gritty of the policies of the new administration, I would like to do a brief overview of the state of affairs presently in terms of Americans’ livelihood. This will also allow us to appreciate how much room or lack of room we have, if we were to face a deeper recession in the near future.
In America today, there are over 22 million people who are making less than $15/hour and nearly 40 million people who are earning less than $17/hour. The federal minimum wage has not been raised since 2009 and remains $7.25/hour.

There are 20 out of the total 50 states who are still at the bare minimum wage of $7.25/hour.
Here is a list of all the times the federal minimum wage was increased from 1978 to 2009 (if you want to look at the full list that started in 1938 you can access it here at the US Department of Labor website).

The US dollar has had an average inflation rate of 2.53% per year between 2009 and today, producing a cumulative price increase of 49.06%. This means that today’s prices are 1.49 times as high as average prices since 2009, according to the Bureau of Labor Statistics consumer price index. This means that $100 in 2009 is equivalent to $149.06 today.
And in just four years (Jan. 2021- Jan. 2025) inflation on food prices has increased by 21%. This means that $100 in 2021 is now equivalent to $121.00 today. This is a big decrease in purchasing power because it is the prices of goods that are increasing by this much, not the wage. Minimum wage is not increasing based on the inflation rate. Thus, inflation means everything gets more expensive for the US consumer, especially for those in the lowest income bracket.

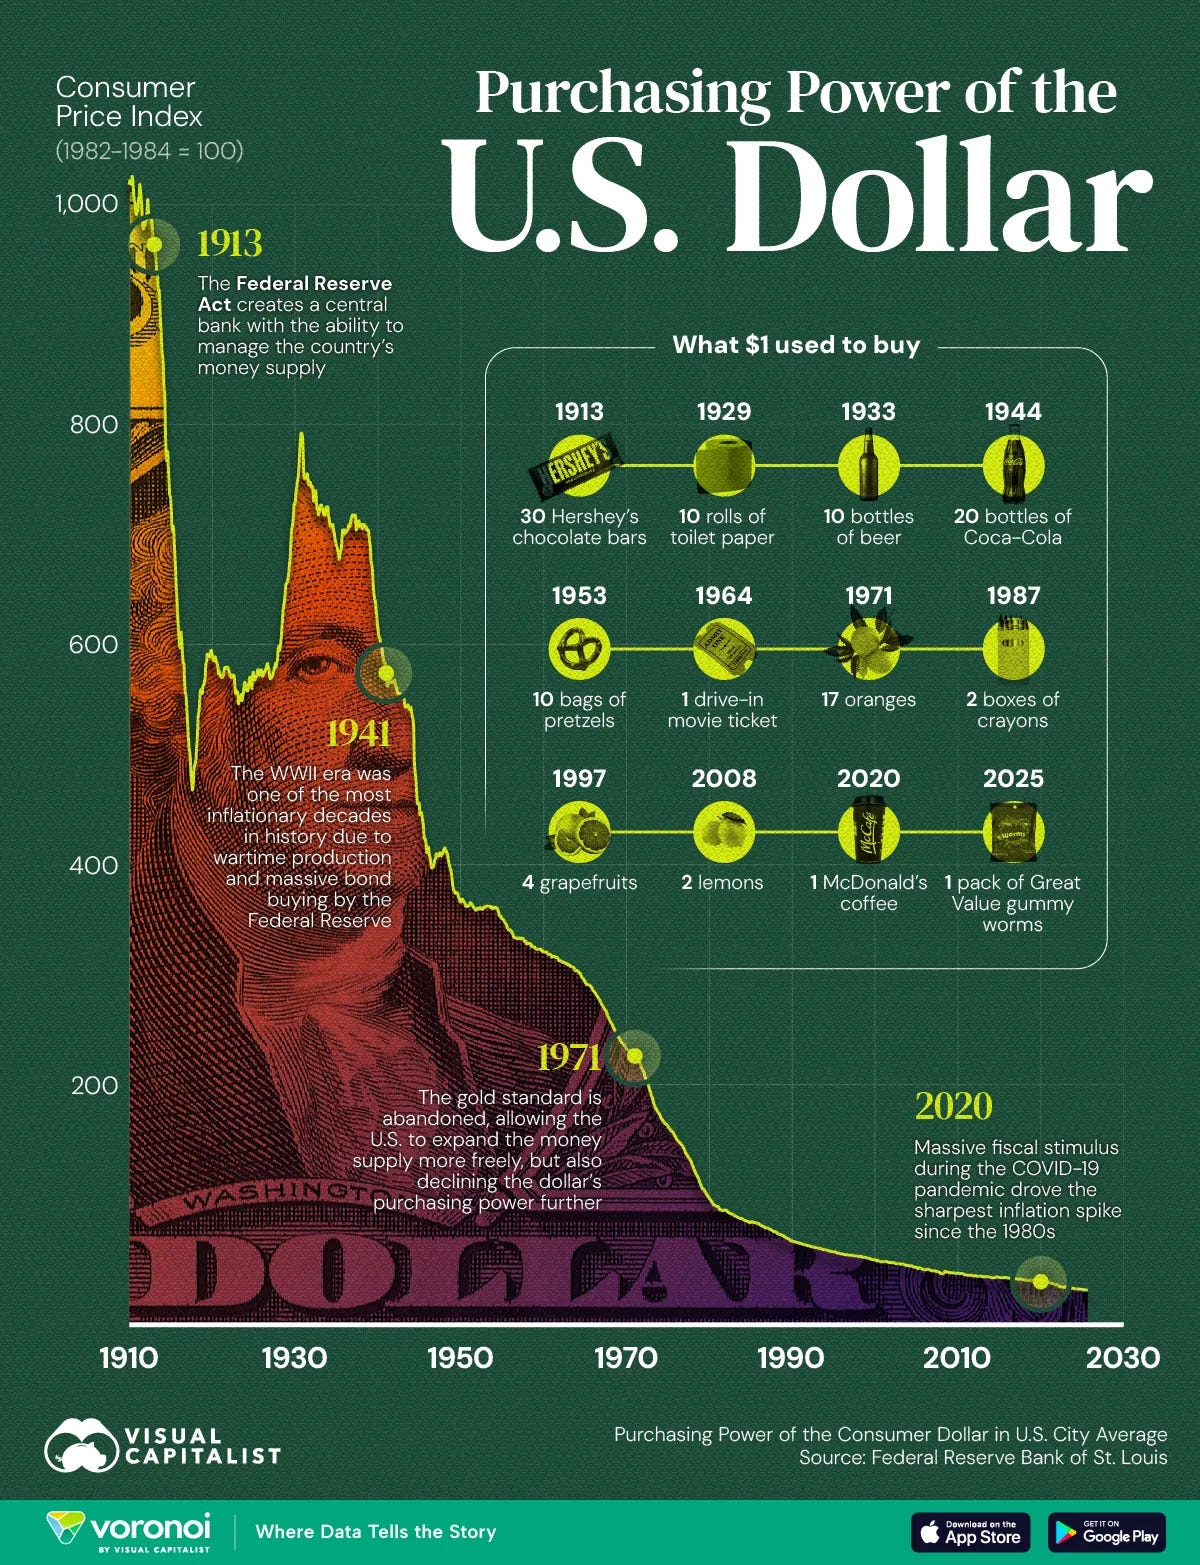
So this is very telling about the decline in living standard that is occurring within the country at an incredible pace.

In addition, companies like Walmart who received staggering tax breaks from Trump’s new tax reform have failed to lower prices. This begs the question, if these massive companies who provide essential services to the public, receive massive tax breaks and do not lower their prices, how is this benefiting the average American? In addition, the tax breaks mean revenue to pay off the US debt will have to come from somewhere else, we will talk about who will ultimately foot the bill for these massive corporate tax cuts.
The Kobeissi Letter writes:
“US credit card defaults have jumped to $46 billion in the first 9 months of 2024, the highest since 2010. Credit card defaults are now up over 50% year-over-year. Defaults on seriously delinquent credit card loan balances have more than doubled over the last 2 years.
Bottom income consumers were hit the hardest due to years of elevated inflation and interest rates. Additionally, the savings rate of the bottom third is now 0%, according to Moody’s.
The credit card bubble is popping.”

Delinquency for a credit card loan means you are late in your payments (even by one day) or miss a regular installment of payment or payments. A credit card loan goes into default when the borrower fails to keep up with ongoing loan obligations or doesn’t repay the loan according to the terms laid out.
I should add here that the spike in credit card defaults in 2010 was from the 2008 financial crisis.
According to Fortune’s article “Americans are increasingly falling behind on their credit card bills, flashing a warning sign for the economy”:
“In the 12 months that ended in September [2024], consumers who didn’t fully pay off their monthly credit card bills paid $170 billion in interest, according to the FT. Consumers may not see much relief soon.”
What this means is that for US consumers who didn’t fully pay off their credit card bills, congratulations you have just made Wall Street richer.
In other words, US credit card interest payments to Wall Street came to a staggering $170 billion in just 12 months, from September 2023 to September 2024. This is insane. And guess what, rates are not looking like they will be dropping any time soon. However, survival from now till then isn’t guaranteed.
[Author’s note Feb 12, 2026: As of today, President Trump has NOT lowered credit card interest rates despite having strongly advocated that they should be capped at 10%. This was one of the loudest promises Trump made as one of the first things he would do when he entered office in 2025, what happened?!?]

The reason why we are seeing a higher default in credit cards is because of increasing inflation as well as high credit card interest rates. For those proportion of Americans who are increasingly unable to keep a decent living standard as prices get higher, they are forced to go into credit card debt to pay for groceries, or their utilities bill. This debt then charges exorbitant interest rates of 20-25% trapping Americans into losing even more of their salary and making it harder to pay off the debt. In addition, people are swiping their credit cards more today than during the 2020 lockdowns. We are near the desperation level just after the 2008 housing collapse.
Many Americans cannot afford to default, this is really a sign of a desperate situation for the most part, because once you default your credit rating is ruined. This means you will likely either be refused a credit card from another bank or you will be charged even higher interest rates since the risk of you defaulting is high. So you lose even more of your salary to even higher interest rates.
We can see from this pattern that those who are low-income wage earners are hit from multiple angles to lose more and more of their salary to inflation and interest payments.
35% of the average American paycheque goes to debt and that includes your mortgage and car payments. Recall that the savings rate for the bottom third of Americans is 0%. That is approximately 114 million people.
CNBC writes in their article “Many Americans are still living paycheck to paycheck”:
“Around 35% of households earning less than $50,000 per year are living paycheck to paycheck, up from 32% in 2019.”
An increasing number of Americans today cannot afford to own their car fully, they are either on a monthly payment plan or are paying a rental fee. However, a growing number of Americans cannot even afford a monthly payment plan at this point.
Granted there is an increasing risk to lenders during a time when defaults are rising. Credit lenders wrote off an incredible $46 billion in delinquent loan balances in the first nine months of 2024. This is up by 50% in the same period the year before, so people are poorer today than in 2023. And this is the effect of higher inflation plus higher interest rates ravaging the economy. But recall, there was still a total payment of $172 billion over 2024 to Wall Street on just the interest on credit cards, so profits are still extremely high for lenders at the expense of Americans’ livelihood.
The point in all of this is the undeniable fact that an increasing number of Americans, 35% and rising, cannot afford their present living costs and something will have to give. The Titanic is sinking and there are only so many life jackets to go around.
Below is a map on the percentage of housing that is affordable within the United States. For example, the state of California has a 33% home affordability. What that means is that 33% of houses listed for purchase are listed at what is considered an affordable price for those living in that state. We can see affordability rates as low as 23% in Wyoming, 25% in Oregon, 21% in Connecticut, 29% in Washington DC. And the states with the highest affordability rates only scored in the 40% range, except for just three states who scored higher than 50%: Virginia at 54%, Maryland at 57% and Delaware at 69%. However, these statistics are representative of the housing situation in 2021, with the crisis of housing affordability much worse today.

One reason for this lack of affordability is Blackstone, who has been investing for many years in buying up infrastructure and is the world’s largest commercial landlord.
The Guardian writes in their article “The Blackstone rebellion: how one country took on the world’s biggest commercial landlord”:
“Blackstone is the largest commercial landlord in history. Over the past two decades, it has quietly taken control of apartment blocks, care homes, student housing, railway arches, film studios, offices, hotels, logistics warehouses and datacentres. Blackstone doesn’t just own real estate, it owns everything – or that’s how it can feel when you start to examine its bewildering array of assets.
…. Last year, the company invested $270bn, bringing the total value of the assets it manages to $881bn, slightly more than the gross domestic product of Switzerland, and more than twice that of Denmark… Blackstone is an asset manager, a type of private financial firm that invests the wealth of pension funds and insurance companies. It is not to be confused with BlackRock, an asset management firm founded by Larry Fink, who worked for Blackstone in the 1980s and set up its bond-investment business. In 1994, BlackRock became an independent firm and Blackstone sold its shares in the company. Fink and Schwarzman now work on opposite sides of Park Avenue. Fink’s company dwarfs Blackstone, but when it comes to property, Blackstone is the giant. Its $320bn real estate portfolio is more than six times larger than that of BlackRock. ‘For Blackstone, real estate is the goose that lays the golden egg’.
… But it is Blackstone’s interest in another type of real estate that has attracted the most scrutiny. In recent years, it has become known for creating a profitable asset class from residential properties – in other words, buying up homes.
… The company has acquired houses and apartments at a voracious speed in cities around the world. Like any company, Blackstone is focused on creating returns for its investors [the billionaire class that is]. Residents in some Blackstone properties have accused it of raising rents while reducing overheads, and the company has even been blamed – by an adviser to the United Nations – of helping to fuel the global housing crisis...”
In the New York Post article “Blackstone Sees Green from Subprime Loan$” published July 25, 2008 in the middle of the housing bubble bust:
“Homeowners having trouble making their mortgage payments may soon find themselves working out a payment plan with buyout kingpin Steve Schwarzman.
Schwarzman’s private equity firm, The Blackstone Group, recently announced it is prepping to make bets in the toxic subprime market.
And now, The Post has learned, it has set aside $1.25B to do this through a partnership with Florida firm Bayview Financial.
The plan is to use Bayview’s mortgage servicing arm to locate troubled loans on the cheap, including those where payments have stopped.
Once Bayview locates a loan, it will renegotiate the terms as needed, such as to get laggard payments back on track. [In other words, they are loan sharks]
Blackstone can then turn around and resell or ‘securitize’ the loans for a profit. Blackstone also has the option to take hold of properties when mortgages default.
… Also drooling over the downtrodden residential-mortgage market are hedge funds Fortress and Och-Ziff, as well as traditional asset manager BlackRock.”
In the case of Fort Worth, Texas, 26% of single-family homes are now commercially owned. What that means is that property buyers will be, or already are, priced out of the homebuying market.

It is literally the plan of “you will own nothing and be happy” agenda so blatantly laid out by the World Economic Forum because even though they know that will outrage the greater majority of people – they consider you irrelevant.


So increasingly, even people who can theoretically afford to own a home are being squeezed out by massive buyouts by commercial interests. Increasingly overtime, there will no longer be any homeowners, only renters according to this trend.
And I would gather that this phenomenon in Fort Worth is not a coincidence. Within Fort Worth is the billionaire Walton clan who are the world’s richest family…and happen to be the owners of Walmart.
Culture Map writes in their article “Fort Worth billionaire and family reign as the world’s richest clan”:
“In once again crowning the Waltons the world’s richest family, the Bloomberg news service recently reported [in 2021] that their collective fortune had risen by $23 billion in the past year due to the climbing stock price of the Walmart retail chain. Sam Walton opened the first Walmart store in 1962.
Descendants of Sam and his brother, Bud, control more than 1.3 billion shares of Walmart stock either directly or through family trusts, Bloomberg says. Even though the Waltons have liquidated $6 billion in Walmart stock this year, they’re now worth more in 2021 than they were in 2020.
As of mid-September, the Waltons were worth $238.2 billion, according to Bloomberg. That’s almost $100 billion above the next richest family in the world, the Mars family of candy and pet care fame. Last year, Bloomberg pegged the Waltons’ fortune at $215 billion.
To put the Waltons’ one-year, $23 billion bump in wealth into perspective, Bloomberg estimates the net worth of Walmart heir Lukas Walton at $22 billion.
Alice Walton ranks as the second richest person in Texas (No. 1 is Elon Musk, at more than $200 billion), but she’s not the richest Walmart heir. As of September 27, Bloomberg estimated Walton’s net worth at $61.9 billion, making her the 19th richest person in the world. Ahead of her are brothers Jim ($63.7 billion, No. 17 worldwide) and Rob ($63.3 billion, No. 18 worldwide).”
This again calls into question why President Trump thought he needed to give Walmart one of the biggest corporate tax cuts in 2025 while the American consumer and producer were left with a heavier load.

Private Equity Stakeholder Project (PESP) and Alliance of Californians for Community Empowerment (ACCE) released a report in March 2023, titled “Blackstone Comes to Collect: How America’s Largest Landlord and Wall Street’s Highest Paid CEO [Schwarzman] Are Jacking Up Rents and Ramping Up Evictions.”
On their website they write:
“The report highlights San Diego County, where private equity firm Blackstone purchased 5,600 naturally occurring affordable housing units in 2021 and how, as units become vacant, the company has raised rents in some units between 43-64% in just 2 years, (AB 1482 pegs annual raises above 10%, for existing tenants, as price gouging).
As San Diego becomes increasingly unaffordable, throwing more families into homelessness, Blackstone’s aggressiveness as the third largest landlord in the area in hiking up rents for its thousands of units only adds to the problem…By jacking up the price of their units Blackstone is rapidly dwindling the number of affordable housing units in the area – exacerbating an already dire affordable housing shortage.
Key Points from the Report:
- Blackstone owns and manages over 300,000 units of rental housing in the U.S., making it the largest landlord in the U.S.
- In the last two years, Blackstone has been on an aggressive buying spree, expanding its residential real estate empire by snapping up various single-family and multi-family rental properties, adding over 200,000 housing units to its portfolio.
…
- Blackstone also spent millions of dollars fighting against rent control in California. Blackstone gave over $7 million in 2018 and more than $7 million in 2020 to oppose statewide ballot initiatives that would have limited rent increases.
But it gets even worse.
ProPublica writes in their article “This Doctors Group Is Owned by a Private Equity Firm and Repeatedly Sued the Poor Until We Called Them” how Blackstone Group has acquired one of the nation’s largest physician staffing firms in 2017 resulting in low-income patients facing far more aggressive debt collection lawsuits.
But it is not just Blackstone that is acting as a predatory private-equity firm buying up everything it can get its hands on.
Scott Bessent has said that he plans to further privatize the US economy and deregulate the banks as part of his medicine for sick America. But I think the jury is no longer out on this, privatization is not making things run more smoothly or responsibly but rather is having the very opposite effect. People’s rights are being violated to a horrifying level, with increased evictions, exorbitant hikes in rent of up to 60% in two years, and criminal negligence and recklessness in the medical field. And the deregulation of the banks is what made catastrophes like the 2008 financial crisis possible, where Wall Street came out on top while those who paid were the American people.
In case you didn’t notice, private equity firms like Blackstone made their biggest profits during the 2008 crash and the 2020-21 lockdowns. These were periods of massive wealth transfer from the low and middle income earners to the multi-millionaire and billionaire class.
This is going to feed deeper into the class divide that is already occurring in the United States. However, never to miss a business opportunity, since let us remind ourselves that the bottom third of America’s population still amounts to 114 million people and thus there is still millions to be made off this impoverished sector. With credit card default rates sky-rocketing what do we see emerge through the cracks of the system? The new economic framework for the downtrodden who own nothing, the “Buy Now, Pay Later” new debt economy. Excited?!

Here's what US consumers had to say in a poll about the “Buy Now, Pay Later” experience.

I think we have a pretty good idea of how this new framework is going to suck people who are already struggling dry. With a growing number of Americans entering into the low income bracket, and round up into one gigantic pig pen within a debtor economy, we can see a point where desperation is going to reach a peak. And what will happen then? An entire overhaul of the system with a new framework will be announced, likely with a global vision (recall private equity firms like Blackstone are global), and it might just be Scott Bessent himself who will have the honor of making this very announcement to the American people.
After all, he is Wall Street’s “man.”
US Billionaires Unite to “Make America Great Again”
It is interesting that Trump keeps referring to the “unfair treatment” Americans have received in trade relations with the world. And thus, his justification for implementing tariffs onto the entire world (i.e. a revenue tax on the world), including their closest allies, as a means of taking back revenue that has been, according to Trump, unfairly lost in global trade.
As already mentioned in Part I of this series, there is $9.2 trillion of US debt this year that will mature or need refinancing. That is about 25% of the total US debt that has come a knockin’ this year alone. It is clear that these tariffs are to function as a revenue tax as a means of generating revenue to pay this debt off.
[Author’s note Feb. 12, 2026: As we see from the 2025 stats, this revenue was in fact generated from the American consumer and producer, not even its foreign competitors, further stripping down U.S. manufacturing and lowering the standard of living for the average American.]
If the US defaults on its debt, you can basically kiss goodbye to the US dollar system as hegemon in global trade transactions. If this were to occur, the US would lose any power to sanction other countries. The world would effectively be able to trade as they please with other countries without incurring punishments or risk themselves being sanctioned by the US. In other words, the US is going to lose the big stick it has been using.
[Author’s note Feb. 12 2026: Here are some charts showcasing the performance of the US dollar over the past year.]
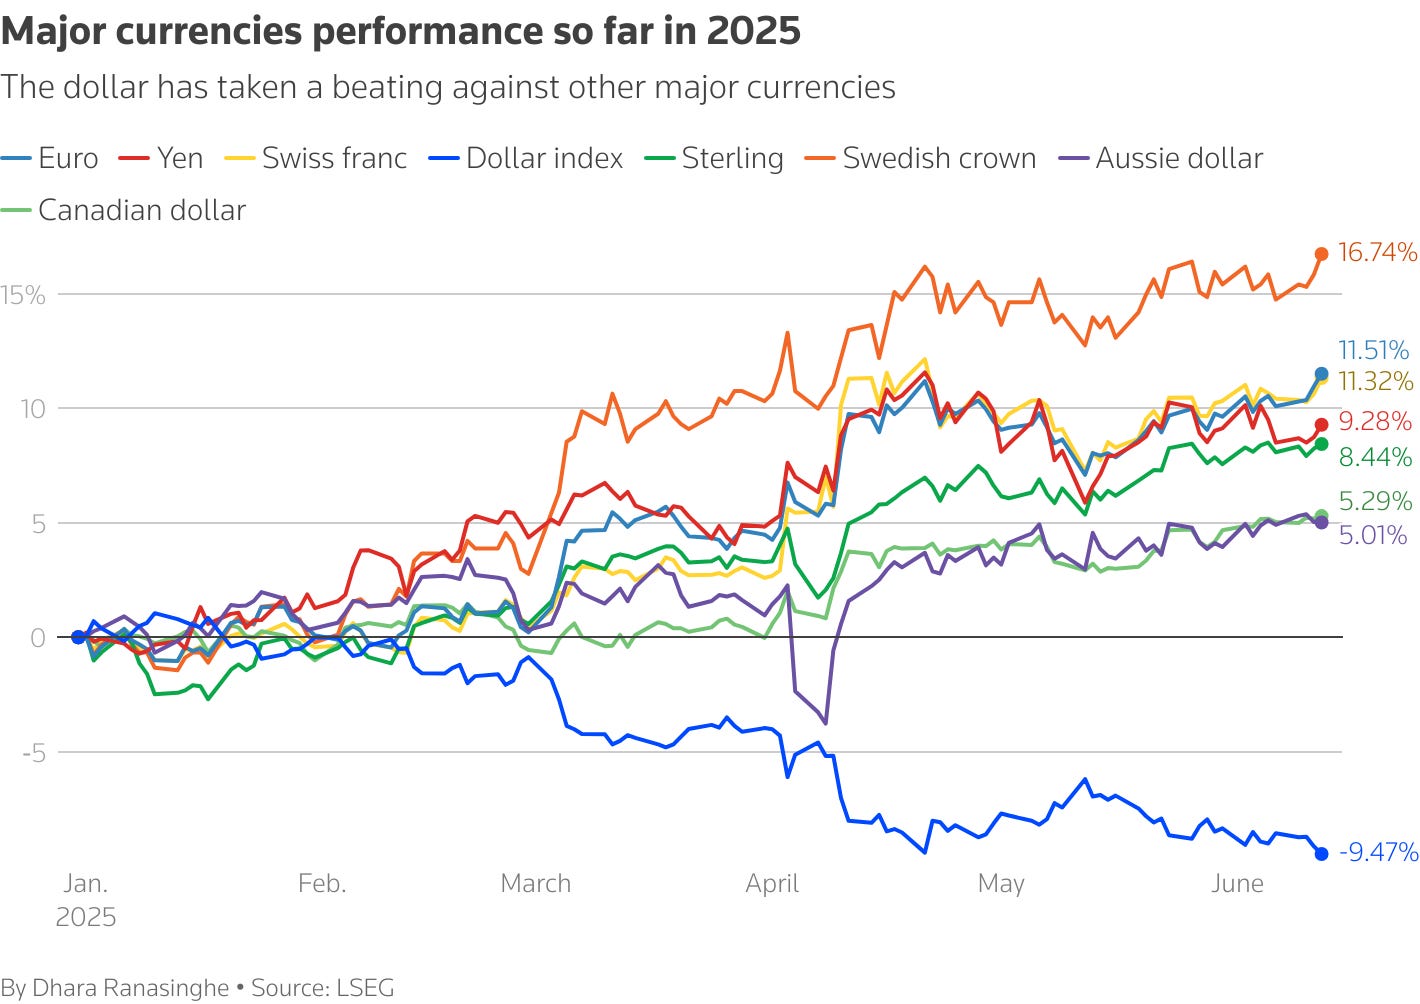
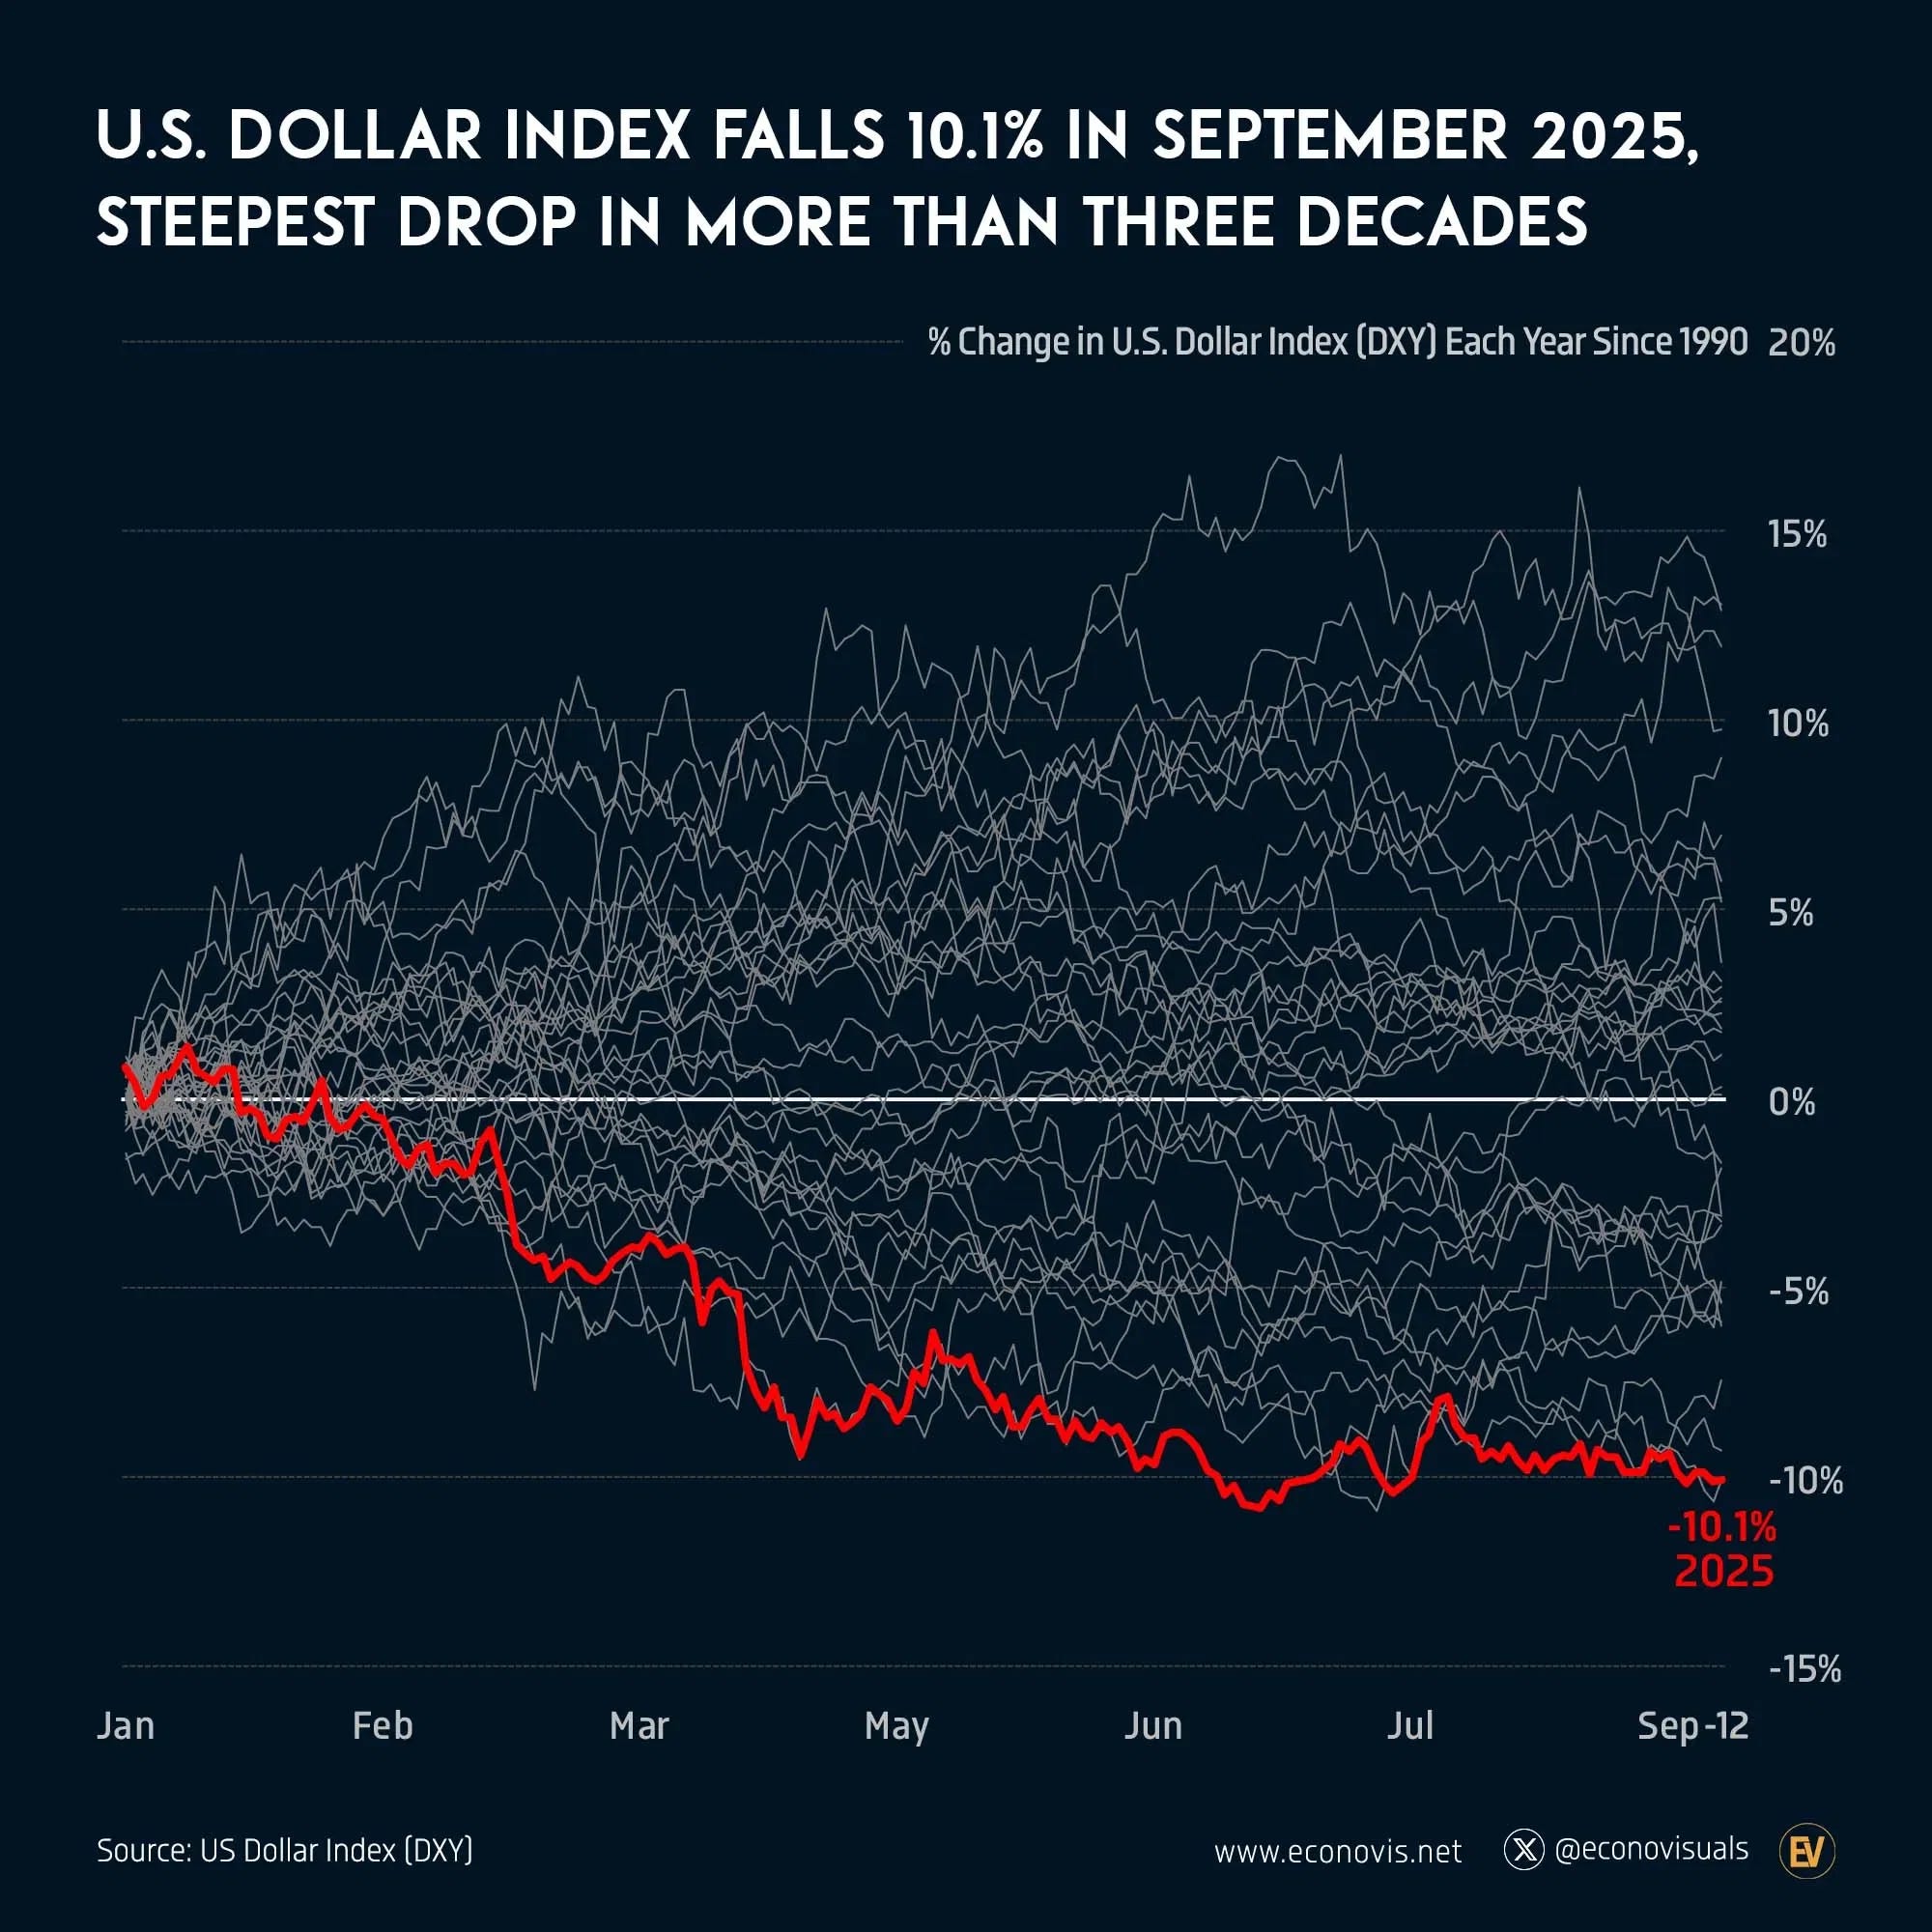
As we can see in the above graphs, the US Dollar as the world’s leading reserve currency is beginning to lose its global hold. In other words, the world is moving towards de-dollarization.

There are many reasons for this, one very notable one is that the US has been very liberal in its sanctioning of countries including Russia, Iran and Venezuela who are big resources for energy. Increasingly we see countries around the world using their own currencies to purchase from sanctioned countries. One big commodity in these trades is that of oil, to which Russia, Iran and Venezuela are all large producers of. In fact, Russia has been selling a great deal of its oil in the Chinese currency, the yuan, ¥.
China as well has been trading more and more using their own currency and the dollar is no longer a part of a huge portion of global trade transactions. Over 50% of China’s cross border trade is in their local currency. And in the first 8 months of last year, payments increased by over 21%. The BRICS nations are increasingly avoiding the dollar in their transactions with each other and their trading partners. And Russia and China are now actively launching an alternative payment system to SWIFT (Society for Worldwide Interbank Financial Telecommunication).
This is the so-called “national security threat” from the BRICS nations that the United States has been ruffling its feathers over… That they dare trade amongst themselves freely. However, what did you expect? For countries to allow themselves to be contained in a cage and told what they can and cannot trade in for vital resources such as energy needs? In addition, sanctions have been used as an excuse for even going so far as to deny countries humanitarian aid, such as after the 2023 earthquake in Syria. Iran has also been denied access to crucial medicine for many years now.
Are we in the west truly thinking that we should have the right to determine such a fate for people in the world, and are surprised when they do not obey such orders?

As the US dollar loses its status as the world’s leading reserve currency, this also affects their ability to find investors to buy up their debt, in the form of treasury bonds and thus avoid defaulting on the massive $36 trillion and growing. You can see how dizzingly fast this debt is expanding on the US Debt Clock.
This debt can either be paid through surplus revenue, that is the big sales pitch for Bessent’s global tariff strategy to Americans that has claimed will generate “revenue.”
[ Author’s note Feb 12, 2026: As we can appreciate now, revenue was generated from the American producers and consumers to foot the bill to pay for a debt that is expanding faster than it can be paid and is eating away America’s manufacturing base and living standard at an increasing pace.]
DOGE is already pretty much a failure at this point, seriously under-performing from the promise of $2 trillion in savings during the Trump campaign.

After less than four months, Elon Musk is walking away from DOGE to focus on his own company, Tesla, after a dramatic drop in its stocks.
When one considers that the 2025 military budget has risen to a record-breaking $1.035 trillion… That is to say, a nearly $150 billion increase from the 2024 defense budget- we see that the so-called “revenue” made by DOGE simply went straight into the military industrial complex.
Recall from Part I that the selling of many more US Treasury Bonds are key to not defaulting on the $9.2 trillion owed this year. In other words, that investors, especially foreign investors agree to buy this debt and hold it. However, this hot potato is becoming too hot to hold for very much longer.
US bonds, which used to be considered extremely low-risk, pretty much zero risk, are now considered very, very risky. This is very, very bad. Since the US economy, after decades of gutting their industry have become a financialized economy. In other words, Wall Street has been generating “revenue” through betting on things, it is a casino economy.
However, what was central to all of this working with the illusion of power and luster was the “faith” in the system, the belief in the US dollar. But the cracks in the ship are now clear for everyone to see. It isn’t going to stay afloat much longer.
In other words, it is a very desperate situation.
Recall from Part I of this series, that foreign investors dumped a massive amount of US treasury bonds as a reaction to the world tariffs, which was made worse from the announcement of the reciprocal tariffs. It also didn’t help that there was a lot of flip-flopping from the Trump Administration and lack of clarity as to what these tariffs would be and for how long. Investors absolutely hate this sort of uncertainty, and they are more likely to walk away from it and wipe their hands clean of the mess. It caused a massive loss in confidence in the US markets during a time when confidence was already extremely low from foreign investors who can simply take their money elsewhere.
This massive dumping of U.S. bonds, in turn, increased the treasury yield making them a riskier investment, which caused a further drop in investors purchasing these bonds. In other words, this happened at the absolute worse time, when bond purchases need to increase (massively) they have in fact decreased (massively) making the paying off of the US debt that much more challenging and the risk of default that much higher.
A higher yield also means the borrowing rate will be higher, i.e. interest rates (since the treasury yield is high). This means all interest rates across the board will be higher - including house mortgages, or businesses that need to borrow money to, for instance…rebuild manufacturing in the United States to “Make America Great Again”!
This in turn is going to have the effect of increasing the cost of rebuilding US manufacturing since there will need to be borrowing for this massive project that is going to cost hundreds of billions of dollars, and this borrowing is going to occur in an already high-interest rate environment which just got higher after the March/April mayhem.
Think about it, everyone knows that Day X is coming, the day the US will default on their debt. The US dollar’s hegemony is based off of the belief that that day the US defaults on their debt won’t be anytime soon. However, increasingly the world is thinking that day is very, very close by.
This begs the question, if the current US strategy is causing more countries and foreign investors to dump US bonds won’t that trigger a bigger explosion in US debt? Right now, the prevention of further loss in US Treasury bonds and the selling of more are essential for the US to have any hope of not defaulting this year. Many analysts think this is the real reason why there was a 90 day “pause” on the reciprocal tariffs. They could not afford to risk any more carnage in the stock and bond markets.

In goods alone the US has an incredible trade deficit of more than $1.3 trillion. The US imports a ton of goods from China, Mexico and Vietnam. The manufacturing base back home is almost non-existent. But because of this the world earns a ton of dollars from US importers. Well over a trillion is flowing out to foreign companies that make the goods that US consumers purchase. And what do people do with the dollar earnings? A big part of it comes back to US investments.
Investors in China, Mexico and Japan, then start buying up US assets, like stocks- as a result stock values continue to rise. The US trade deficit is a big reason why, for the last few decades, the US stock and bond markets have been flying up - at the cost of the US manufacturing base and living standard.

America will have to spend billions upon billions of dollars to build back US manufacturing – while simultaneously needing to raise TRILLIONS to pay off a massive debt. Even if Trump is successful in getting key industries to re-shore to the US, this is not as simple as moving a piece on the chessboard from one place to another. And for advanced technology factories you need an industrial ecosystem to build up your factories. You can’t just expect to build cutting edge facilities, literally in the middle of deserts (i.e. semiconductor TSMC plants), within a year or two.
In addition, these industries based in the US will now be facing greater costs in manufacturing - prices for supplies will be higher since they need to import many of their materials in because the US produces very little domestically at this point after over 60 years of deindustrialization in favor of a debtor economy.

In other words, most of these factories, especially advanced sector industries, are going to require supply chains from outside the United States. The US has not built up its own supply chain capability, so these manufacturers within the US will be hit with the tariffs on supplies they need to import to build and run their industry.

These were the original reciprocal tariffs planned for April 5.
[Author’s note Feb 12, 2026: The below graph is a more up-to-date reference for the rates of the reciprocal tariffs imposed by the Trump Administration globally.]
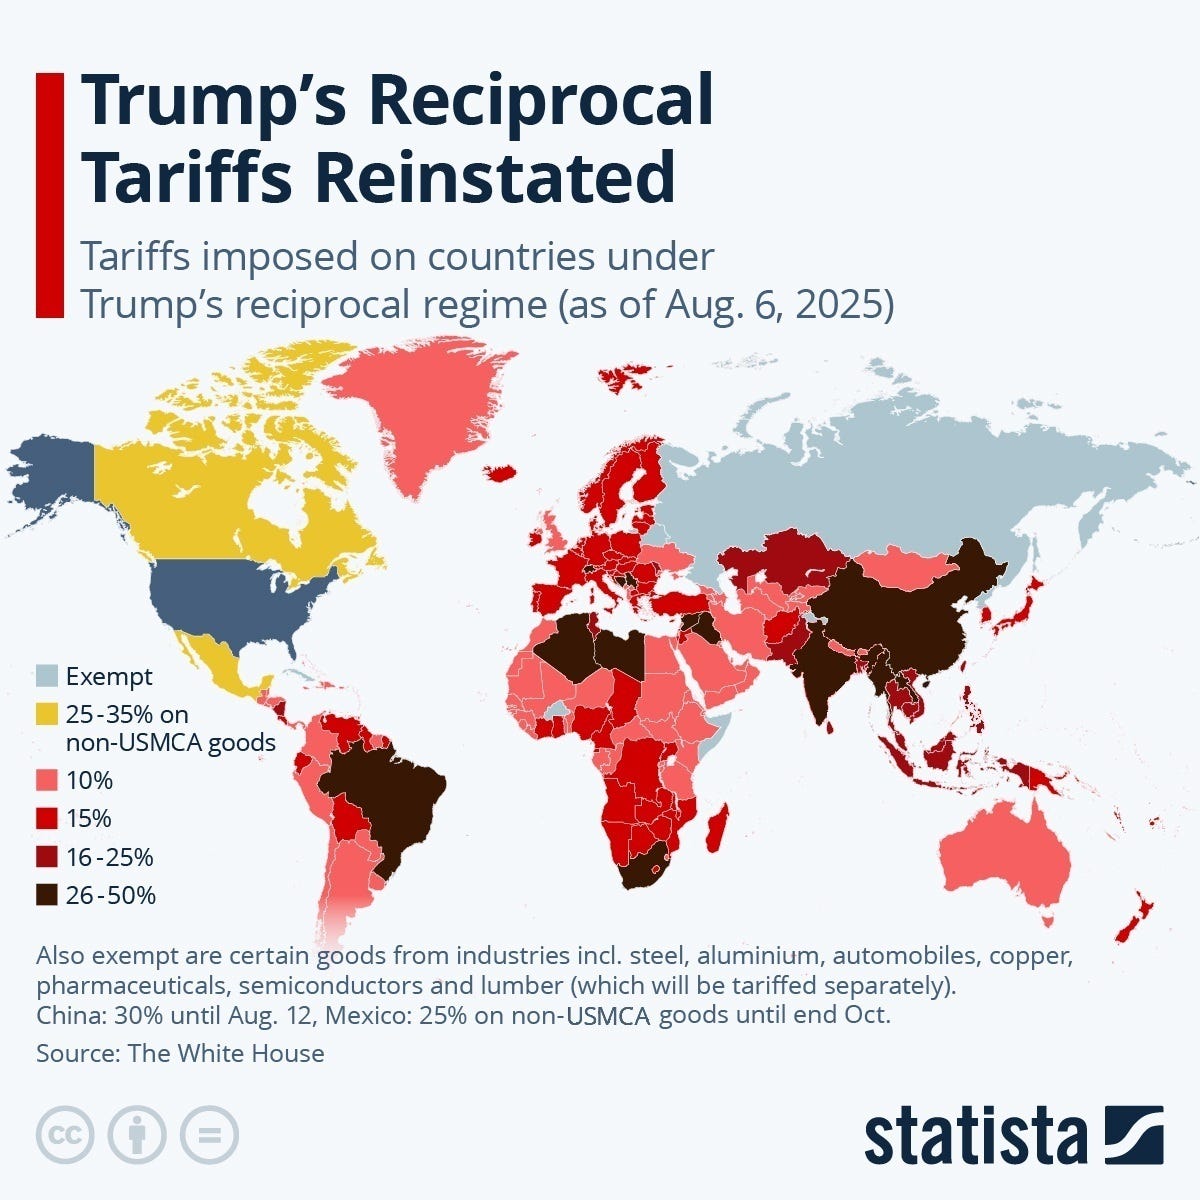
We should understand here that Bessent’s tariffs on the world have been used more as a weapon than a form of protection, and pose a very serious threat. This was not some little bit of extra tax that was being enforced here. The Trump team made it clear that these tariffs were meant to be crippling such that countries all over the world would have no choice but to make a “deal” with the United States.
As for these “deals” we have seen that they are a shakedown of each country in terms of what the U.S. views they can “offer” to the U.S. empire. If you have key strategic industry, the U.S. wants it for their own now.

If you are an economic competitor like Japan, the US wants you to step out of the race. If you are an exporter of resources such as oil, or critical minerals, the US would like you to sell this to them on the dirt cheap, and the list goes on.
[Author’s note Feb 12, 2026: To quickly summarise how the application of the tariffs played out during 2025:
April 2, 2025 U.S. announced a sweeping 10% base tariff on imports from more than 180 countries without trade deals.
A few days later, reciprocal tariffs, ranging from 10% to 100%, were imposed.
After an ongoing dispute between U.S. and China over tariff rates, there was a 90-day agreement in May for U.S. tariff rates at 30% and China’s at 10% between the two countries.
Countries such as Brazil, India and others faced sharp new tariffs. For Brazil, U.S. duties surged to 50%, India’s also surged from 25 to 50% in August as a penalty for continued purchases of Russian oil.
EU, UK, Japan, South Korea, Vietnam, Indonesia, Philippines, Pakistan each secured framework deals and moderate tariff rates ranging between 10-20%.
U.S. - EU agreement established a 15% tariff on EU goods, alongside a $600 billion EU investment into US energy and defense sectors [4] What this means is that the EU, has been forbidden to buy the much much more affordable Russian energy (hence the U.S.’s role in blowing up the Nordstream pipeline for instance) and to threaten the EU to pay much more exorbitantly priced energy from the United States amidst their energy crisis.
Amidst this, the EU is expected to prioritise putting money into their own military-industrial complex and buy American defense products to support the American military-industrial complex, while standards of living are plummeting in Europe and people literally have access to no heating during the winter months.
Japan got the U.S. to lower their tariffs to 15% this past September, but only after they committed $550 billion in U.S. investment and shared broader market access. Is a Plaza Accord 2.0 in the cards for Japan? [5]
South Korea also got the U.S. to lower their tariffs to 15% this past November, after they pledged $350 billion, including energy procurement and shipbuilding contracts. [6]
Vietnam faces a 40% surcharge on transshipped goods (basically as penalty for trading with China). [7]
Taiwan faces tariffs at around 20%. The U.S. has carved out semiconductor exemptions but overall tariff exposure remains substantial due to lack of a full deal. [8]
Mexico and Canada, no new deal was struck before August 1. Canada faces 35% reciprocal tariffs on non-USMCA goods. For Mexico, rates range from 25-35%, depending on USMCA compliance. [9] (USMCA stands for United States - Mexico - Canada Aggrement.)


High risk countries that the U.S. is unlikely to get a “deal” with:
China: Still the fulcrum of global supply chains, China remains covered by long-running Section 301 actions (with certain exclusions extended through Aug 31, 2025) and is exposed to the reciprocal regime absent a standalone deal. Global enterprises should not assume a single “China rate.” [10]
Brazil: Reporting indicates escalating tariffs amid political tensions. Specific headline percentages differ by source and sector. The U.S. treats Brazil as a heightened policy risk until official schedules are posted. [11]
Syria, Laos, Myanmar: Public guidance and news coverage point to ~41% for Syria and ~40% for Laos/Myanmar, reflecting sanctions and limited diplomatic engagement. Expect long-duration tariffs and extra screening on end-use/end-user. [12]
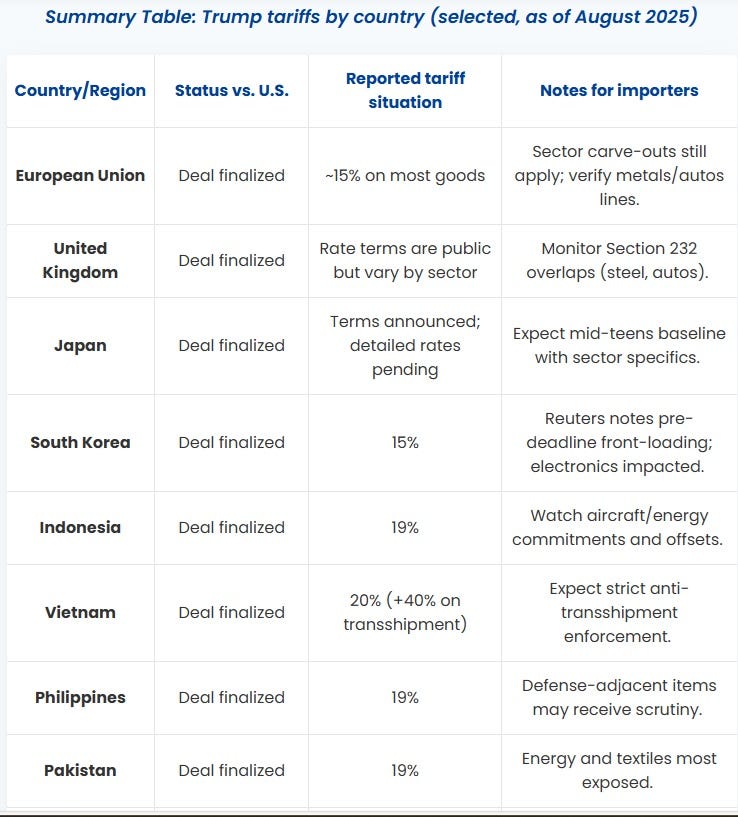
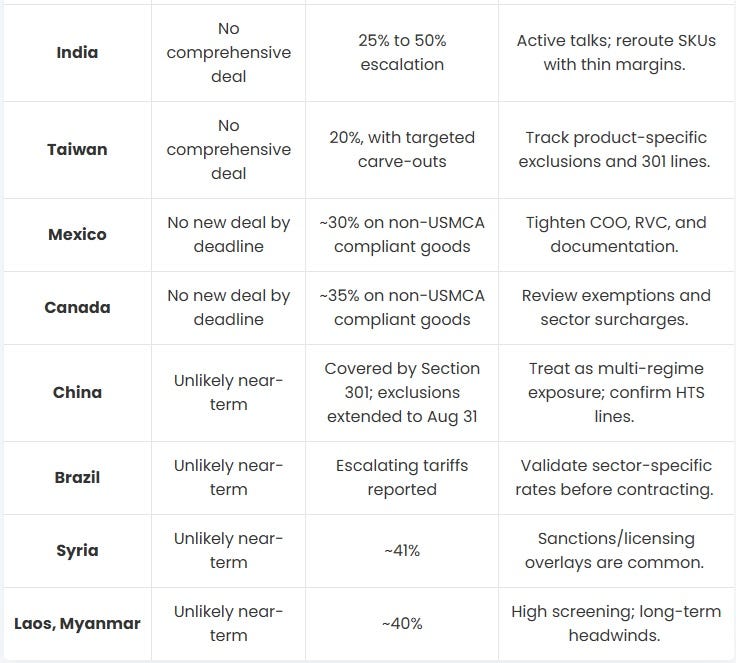
Needless to say, this ongoing instability of predatory tariff rates is causing a great deal of disruption including in supply chains. This is not a benefit to any country’s economic growth, including the U.S., however, it is looking like the United States is only interested in making “deals” that are a benefit to its military industrial complex, and never really had the intention to boost its domestic manufacturing base nor the living standards of its own people.
Now let us get back to my original paper written this past May 2025…]
On top of this, the U.S. has put yet another condition on these “deals,” that all countries forego trade with China. The U.S., who can no longer compete with China, is trying to bully the entire world into not trading with it biggest competitor, through it weaponizing its U.S. consumer market as a gun to the head of countries’ economies.
U.S. Secretary of Commerce Howard Lutnick when asked about whether the tariffs will in fact increase cost in manufacturing, and hence prices to the US consumer, he answered, “Not if you make it in the US.” That is not really true in the current situation. You can avoid the tariffs if you make everything within house, sure, however, the cost of production is higher in the U.S. than for example China because the U.S. is not as streamlined as China. That’s the whole point of the tariff, the U.S. goods cannot compete price-wise with outside goods’ prices. So prices are going to be higher for the U.S. consumer if they were to buy things made in America vs China.
And that is fine, in terms of rebuilding U.S. industry, as long as the prices are not too exorbitant. This is part of the benefits of how a proper use of tariffs is applied. You tariff key sectors from other countries that you cannot compete with price wise, and thus reduce competition with them, such that your consumer base will support the build-up of these domestic sectors within your own country.
So prices were always going to increase for the US consumer, because that is the whole point of the tariff, to raise the competitor’s price for their competing product so you can be supported by the consumer base to build-up domestically. Nothing gets cheaper immediately in this scenario.
The problem here with what Lutnick is discussing is that U.S. Treasury Secretary Scott Bessent has put forward a strategy to tariff everything. Everything coming into the country now just got more expensive, not specific goods/materials. Everything. On top of this trade with China has seriously halted on key materials required for manufacturing that you cannot get elsewhere.
For example, you would like to compete in the manufacturing of cars. This is all fine and good. But you cannot also decide to put high tariffs on steel and aluminum simultaneously! Because the United States DOES NOT in fact produce enough steel and aluminum to meet all of its domestic demand, to which the car industry is just a fraction. So by putting high tariffs on steel and aluminum, which car industries have no choice but to import a portion of their demand, you are increasing costs dramatically for the production of these cars.
You may be thinking, well why don’t we just increase steel production? Yes, this is also a fine and good thing to do. However, it would take years to build up the capacity, which even then would not be able to meet the full domestic demand. Meanwhile, the cost of car manufacturing is sky-rocketing and making it less competive in the global markets. So it is not so simple as putting a tariff on everything and thinking this is going to bolster industry no matter what.
In other words, without a doubt, boosting industry is important and the United States should compete in car manufacturing and steel production on a global scale, however, this strategy will work to undermine industry since the components it needs will be made much more expensive without anywhere for them to turn for a cheaper alternative.
So now, U.S. manufacturers who already had a higher cost of production (and thus were not competitive with global trade) now face ADDITIONAL costs for the materials they need to import to finish their products, which just got more expensive with the tariff strategy. So now U.S. goods are a great deal more expensive, and we are talking about prices that many U.S. consumers simply cannot afford.
This is the very opposite effect of what you would want with a proper application of tariffs. In this scenario, the prices of U.S. goods are going to be so high that U.S. consumers will not be able to afford them and these U.S. goods cannot compete in the global consumer market either, so how are these U.S. manufacturers going to earn their revenue? This is a losing strategy.
And that is what is now backfiring with the Bessent tariff strategy, making the mistake of using them as a weapon against other countries rather than from a protective measure to the benefit of the American economy.
Lutnick seems to think the tariff strategy will act as a motivator for the U.S. to just begin building everything in-house since there is no other choice. But with what supplies? There are no complete supply chains in the United States. You will need to import necessary materials that are not available in the U.S. in order to build your manufacturing industry. There is no advanced industry presently that the U.S. has a complete supply chain in. This won’t just manifest out of thin air! You can’t build supply chains overnight, it takes years. So, this plan is disastrously short-sighted.

Another indicator of short-sightedness from this tariff strategy was the pulling back on tariffs to high tech goods from China, only after a few days of their announcement. Apparently, whoever was in charge of calculating these tariffs didn’t factor in that China was in fact exporting high tech goods to the U.S. that were not easily replaceable. Thus, effectively, the U.S. consumer would no longer have access to these goods…notably laptops, smartphones and essential electronics for businesses if the tariffs had been left in place.

However, when asked on the Face of the Nation about clarification about these exemptions, which were thought permanent, Lutnick said they were only temporary (about one month), contrary to what Trump had given the impression of, since according to Lutnick they would be incorporated into a separate tariff package against China. This left manufacturers and investors in a never-ending lurch as to how to go about managing their companies.
Lutnick has even talked about how these factories will be operated using automation and robotics but how are these advanced robots for assembly lines going to be manufactured? Even if the U.S. knew how to build such robots, which is debatable - the greater majority of the materials required for such a thing would need to be imported. This goes for chip manufacturing as well. It is impossible to build these industries without using China’s supply chain.
The list below mentions just a few critical minerals to give us an idea of how important these are to U.S. manufacturing, especially in advanced technologies, and which are almost entirely dependent on having access to China’s supply chain.


Note, a supply chain does not just mean where these minerals are geographically located, it also means who has the means to process and refine these minerals and metals. When we take into account both the geographical location of these critical minerals and metals plus who has the capability to process and refine them, it is China who comes out on top of these supply chains. And thus, China is the only one who has the capability to complete the circle of manufacturing.

Granted that this above graph is focusing solely on clean energy metals but it gives us a good idea of how China is the only country in the world right now that has the capability of processing and refining almost every critical mineral/metal you would need to build advanced technology industries.
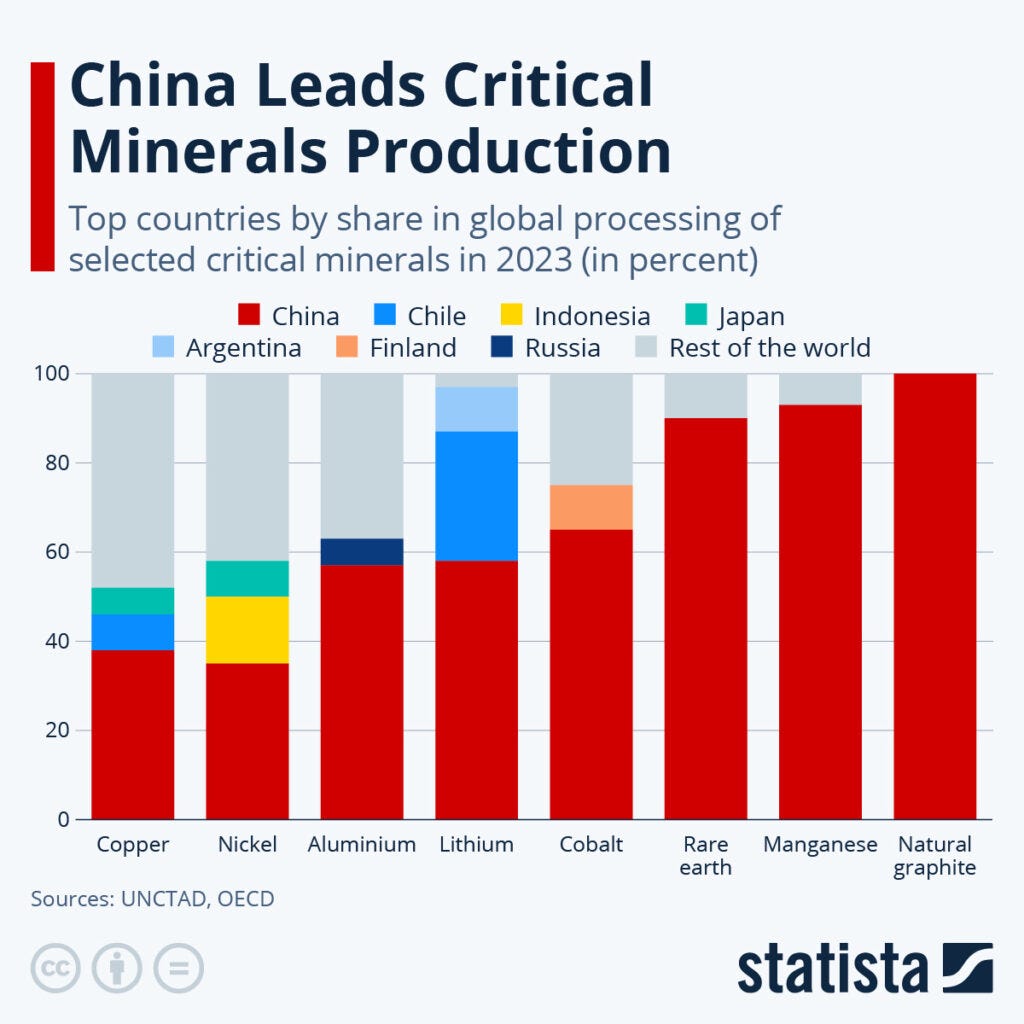
This is why the United States now wants to build up its own capability to control its own supply chains, especially concerning chips/semiconductors. However, this is an endeavour that takes several years to accomplish. China did not build up this capability overnight. For the United States to build up its knowledge and know-how, let alone the actual building of these necessary processing and refining facilities is going to cost billions of dollars on just this alone. Not even factoring in the other billions of dollars needed to build up a manufacturing base, especially if you want to include high-tech robots for assembly lines. So this is a project that is going to take many years and hundreds of billions of dollars in spending before it is even up and running.
America’s return as an industrial leader in high-tech manufacturing is not so simple after decades of the very opposite. Recognise that this is not even discussing the education and training or R&D (research and development) that needs to also be incorporated for this process to go as quickly and efficiently as possible.
Despite the United State’s aggressive posturing against the Chinese government, China has incredibly given an allowance, until recently, for the U.S. to purchase these key critical minerals that are essential for chip manufacturing as well as the manufacturing of military weapons. China has allowed this despite the trade war, beginning in July 2018, which has aggressively sought to cut China’s ability to participate in the chip manufacturing industry.
Here is a summary of the Trump teams’ “Art of the Deal” with China…

[Author’s note Feb 12, 2026: As of early 2026, China has imposed sweeping sanctions and trade restrictions on numerous U.S. defense companies, primarily in retaliation for arms sales to Taiwan. These sanctions typically include freezing assets within China, banning Chinese entities from doing business with them, and prohibiting company executives from entering China.
Following the announcement on December 26, 2025, over 20 U.S. defense-related firms and executives were added to China's sanction lists.
Major Sanctioned U.S. Defense Companies (Dec. 2025- Early 2026)
Based on official, recent announcements from the Chinese Foreign Ministry, the following companies are subject to sanctions:
Northrop Grumman Systems Corporation
Boeing (specifically mentioned: St. Louis-based defense unit)
L3Harris Maritime Services (and other L3Harris entities)
Anduril Industries (and founder Palmer Luckey)
Gibbs & Cox, Inc. (a Leidos subsidiary)
Advanced Acoustic Concepts
VSE Corporation
Sierra Technical Services, Inc.
Red Cat Holdings, Inc.
Teal Drones, Inc.
ReconCraft
High Point Aerotechnologies
Epirus, Inc.
Dedrone Holdings Inc.
Area-I
Blue Force Technologies
Dive Technologies
Vantor (formerly Maxar Intelligence)
Intelligent Epitaxy Technology, Inc.
Rhombus Power Inc.
Lazarus Enterprises Inc.
Previously Sanctioned Major Contractors
Lockheed Martin Corporation (repeatedly targeted, including various subsidiaries like Aeronautics and Missiles and Fire Control)
Raytheon (Missile Systems and Missiles & Defense)
General Dynamics (including Mission Systems and Ordnance and Tactical Systems)
Other Restricted Entities
Skydio: In 2025, China restricted this drone manufacturer, which reportedly cut off their supply chain for batteries.
Additional Firms (April 2025): 18 firms were listed in April 2025 including Shield AI, BRINC Drones, Red Six Solutions, and others.
Nature of the Restrictions
The sanctions, which took effect on December 26, 2025, for the latest batch, generally entail:
Freezing Assets: All assets, movable and immovable, within China are frozen.
Trade Ban: Chinese organizations and individuals are prohibited from engaging in transactions, cooperation, or other business activities with these companies.
Travel Bans: Key executives from these firms are barred from entering China, including Hong Kong and Macau.
The United State’s is heavily dependent on Chinese critical minerals for their military industrial complex, and it looks like China, after one year of the Trump teams’ monkey circus, will not be loosening these sanctions on U.S. defense companies anytime soon. This is a disastrous outcome for the Trump Administration and has ruined what appears to have been the main objective that started this chicken run with China. The Trump Administration thought they could intimidate China and that they would bend the knee and give aid to America’s military empire by pledging hundreds of billions of dollars in investment like Japan and South Korea have done (whether these countries actually deliver on this is another matter). However, China understands if they do this, they can pretty much kiss goodbye to anything resembling sovereignty.]
China has made it very clear that it will not be the first to backdown in this face-off, they have gone all-in and are betting that the United States needs them more than they need the United States in this trade war.
In response to the sound of crickets this past spring/summer 2025, the White House has taken on bizarre messaging to the American people, who were given the impression that this was going to be a cake walk and are beginning to realise that things could get real serious for American jobs and consumer prices.
White House spokesperson Karoline Levitt had this to say as the White House’s stance on the matter:
“The President has made his position on China quite clear. Although I do have an additional statement that he just shared with me in the Oval Office. ‘The ball is in China’s court. China needs to make a deal with us. We don’t have to make a deal with them. There’s no difference between China and any other country except they are much larger. And China wants what we have, every country wants what we have, the American consumer. Or to put it in another way, they need our money’. So the President again has made it quite clear that he’s open to a deal with China, but China needs to make a deal with the United States of America.”
It was certainly not a show of strength when Trump kept acting acting like he was having ongoing talks with the Chinese embassy, only to have the Chinese embassy clarify that there are no talks happening and that the U.S. “should stop spreading confusion.”
So, it’s looking like China really doesn’t care about making a deal with the U.S. and has spent the last several weeks further decoupling from the American economy. The split looks pretty final here and China looks like they have finally had enough of the dishonesty and bullying coming out of the White House over the last several years.
Incredibly, the United States did not put the critical minerals and metals they need from China on a tariff list because they are of course essential for the manufacturing of advanced technologies, including military technologies. However, what were they expecting? That they were going to start a full-out trade war with China and that China was going to continue to sell America these critical materials needed for advanced technology, including military weapons?!?

Or the fact that China is the second highest treasury bond holder in the world and are in the process of dumping these bonds. And can you blame them? Why would China want to fund America’s plan to contain them and cut them out of global trade in hopes of putting a leash on the growing Asian economies? Recall from Part I of this series, Japan and China were the two biggest holders of US debt before the tariff war.
[Author’s Note Feb 12, 2026: China is now third after dumping a bunch of treasury bonds these past months, UK is now second which has been buying up a bunch of U.S. treasury bonds to hold the U.S. debt ship afloat. The two below graphs are updated up to October 2025.
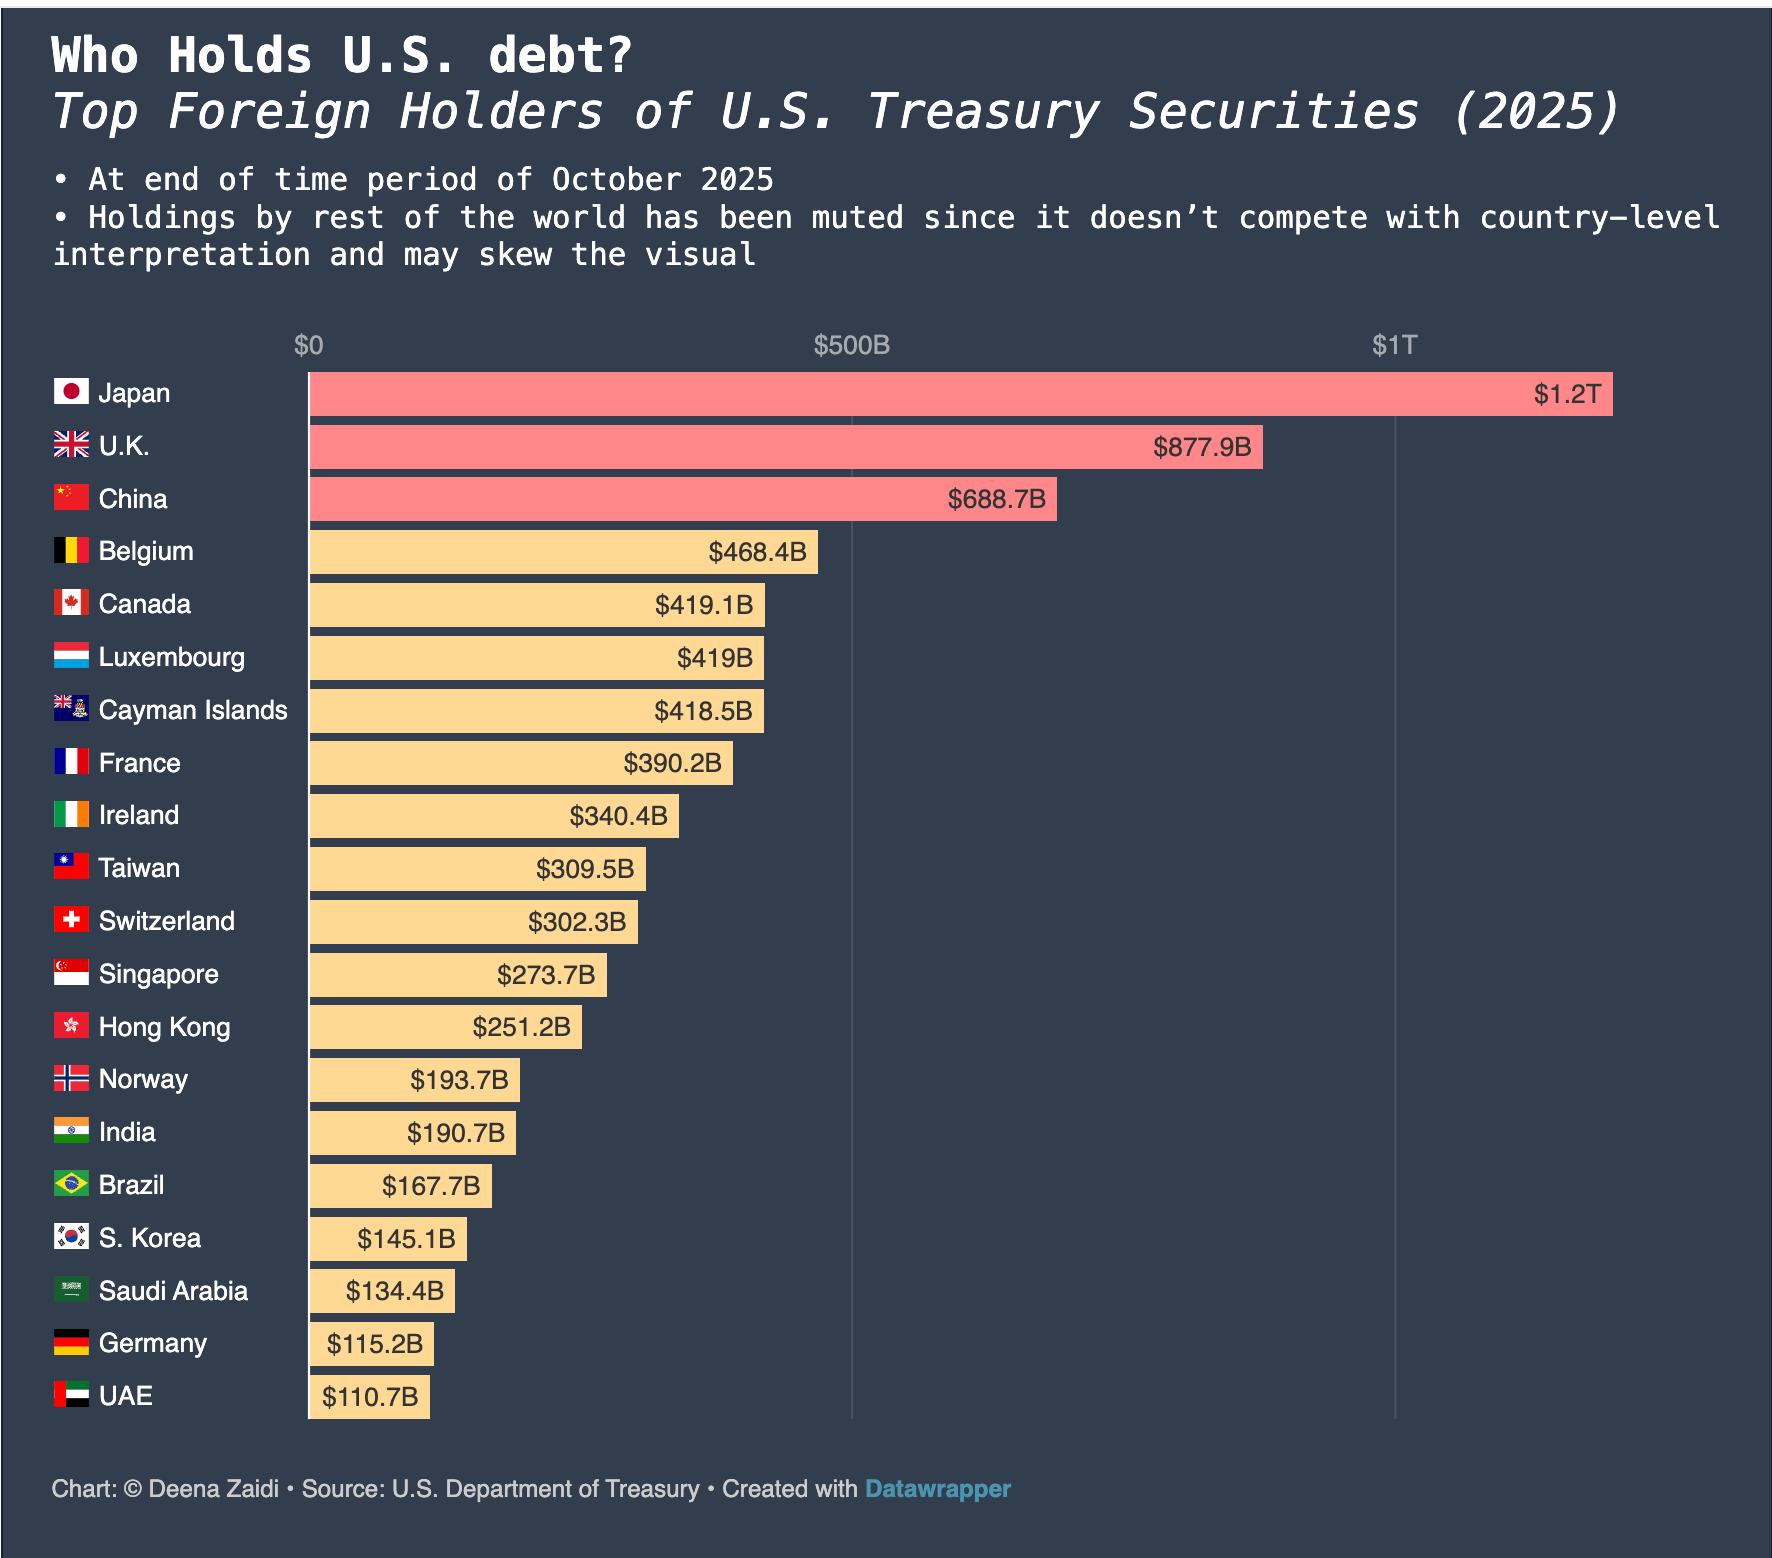
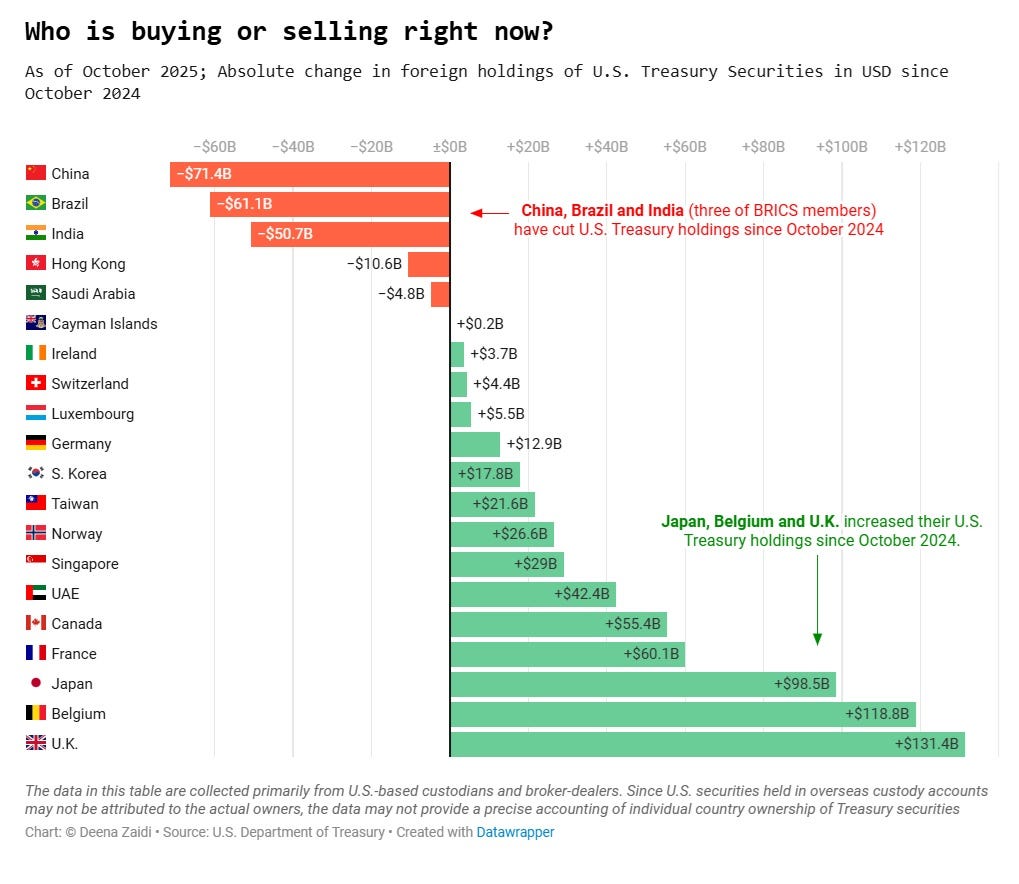
Japan had initially dumped a large portion of its U.S. Treasury holdings during the spring of 2025, but appears to have gotten cold feet since then and is back to its loyal dog status.
China, Brazil and India cutting its U.S. Treasury holdings is showcasing a further decoupling by BRICS nations and their attempt to reduce exposure to U.S. assets which are extremely volatile at this point.
It appears that this is in fact the true intention of Scott Bessent and co. to blow out the system so that a Great Reset can be justified as its replacement. They do not want to save the US dollar, they want to create a new currency for the new world government, which clearly, America sees itself leading. Any country that finds itself trapped in this system will have no choice but to participate in this new global vision. The BRICS nations see the writing on the wall and are attempting to decouple themselves from this sinking ship so that they can have an alternative financial/banking system afloat and will not be put in a position of subservience to the new global empire that will soon be brought online.]
The below graph shows the scary reality of U.S. dependence on China for especially its military needs…

According to Bessent, China is officially in recession, in fact, he believes that Beijing is on the verge of a collapse and that is despite the Chinese economy growing by 5% last year (a growth that didn’t rely on the country going further into debt to inflate that number, unlike the US’s 2.8% growth in 2024).

The US had to go into 6.4% GDP deficit, in order to boost the “real” GDP to 2.8%. In other words, for every $1 spent by the US, they made 50 cents in the year 2024. This is the “growth” of the US economy.
In Bessent’s US Senate confirmation hearing he stated:
“China is the most unbalanced, imbalanced country in the history of the world. They are in a severe recession/depression. They may have minus 4% disinflation. And they are attempting to export their way out of that as opposed to doing the much needed internal rebalance.”
Like becoming a Wall Street debtor economy Mr. Bessent?
This is a very weird statement from Bessent since in the next breath he admits that China still has a lot of money to build infrastructure. If an economy is collapsing they wouldn’t have any money for anything would they?
“China will build a hundred new coal plants this year. There is not a clean energy race. There is an energy race. China will build 10 nuclear plants this year. That is not solar. I am in favor of more nuclear plants.” Bessent confusingly stated.
In fact, China is one of the few countries in the world who are actively building new nuclear plants and are leading this by a large margin.

Notice in the above graph that the United States is still leading in number of nuclear plants, though the number is smaller today since they have been shutting them down over the past several decades. Notice that China has built 39 new nuclear reactors since 2011 when the United States decreased by 11 nuclear reactors.

[Author’s note Feb 12, 2026: There is a present plan by the Trump Administration to build new nuclear plants (which take 5-10 years to build) with goals such as 35 GW of new capacity by 2030 and 15 GW increase per year by 2040. And a goal of 200 GW of new capacity by 2050. Whether these goals will be accomplished or not is another matter, in addition to what this new energy will in fact be used for. Keep in mind that there is a $90 billion investment in data centers and power infrastructure with plans to build 10 large nuclear reactors by 2030. These data centers will be used to a great extent for AI use in applications for the military industrial complex. Data centers require a massive amount of energy. Just something to keep in mind…]
Energy (when it is not used to mainly feed a military industrial complex) is at the core of determining a country’s social progress index. And unlike the situation the U.S. faces, China is not going into debt to pay for this growing infrastructure.

As we can see with the above graph, China now relies on the EU and ASEAN countries for more than half of its total trade. And its trade with the ASEAN countries is expected to increase exponentially since these countries are quickly entering into “first world” economic status. They also house more than half of the world’s population so there is a huge consumer market here, and in the near future will surpass the U.S. consumer market.

China has a SURPLUS of money coming in and they are not throwing it away into Wall Street, they are using the money to actually build up industry. How do you think they have become such a manufacturing powerhouse?

Scott Bessent calls this imbalanced and unbalanced, to the most extreme degree in ALL OF HISTORY. Meanwhile, what is the US attempting to do? Build back its industry so it can be a leader in the export trade since they realise that they can no longer be top dog with the system they were previously operating on, which was controlled artificial scarcity.
China has blown that tactic out of the water because they are offering essential, crucial trade with other countries that will allow these countries to be self-empowered. Look at the entire history of colonialism, they ALWAYS wanted to prevent or put a cap on industrialisation because it was always understood that that would free regions of the world to become self-sustaining. There is no more control if you are no longer the hand that withholds.

Here is a map (to the left) of the colonial rail lines of Africa built by the colonialists of Europe between 1890 and 1960. Notice that they for the most part do not connect with each other, except in South Africa where there are many white inhabitants. These rail lines are from a resource mine to a port and were used simply for wealth extraction and not to uplift the people. I will be doing an updated detailed overview of what China’s BRI is in fact building throughout the world. However, you can refer to my paper, with the subsection “China’s Belt and Road Initiative Put Into Perspective” for something I wrote a few years back. Great resources on this are Lawrence Freeman’s website “Africa and the World” as well as Nicholas Jones’s Substack Nkrumah’s Africa both are also RTF lecturers.
This is what President Putin was referring to in a speech from 2018 to light up Africa.

This map shows how much of the world is still in great need of energy and infrastructure.
In 2019, Reuters reported that the United States’ top African diplomat warned that African countries running up debt they won’t be able to pay back, should not expect to be bailed out by western-sponsored debt relief.
“We went through, just in the last 20 years, this big debt forgiveness for a lot of African countries,” said U.S. Assistant Secretary of State for African Affairs Tibor Nagy, referring to the somewhat condescendingly named HIPC (Heavily Indebted Poor Countries) program, started by the IMF and World Bank in 1996 as a nice window dressing.
“Now all of a sudden are we going to go through another cycle of that? ... I certainly would not be sympathetic, and I don’t think my administration would be sympathetic to that kind of situation,” he told reporters in Pretoria, South Africa.
Hmmm, imagine if a Chinese diplomat were to have said that, how it would have been viewed by the west, but apparently when a westerner says it, it is somehow not exploitive and predatory…
Wall Street billionaire Scott Bessent has even gone so far in interviews to say that China is not only sick and unbalanced for exporting so much, but that these massive volumes of exports must be going somewhere, but acted puzzled as to where that could possibly be. How about to where the majority of the world population lives that is in great need of this trade with China to lift their countries out of poverty Mr. Bessent.
So, there’s an incredible disconnect here. According to Bessent, China is both strong and weak at the same time. Is China an economic rival to which you need to guard against or is China crashing and no longer a threat - because you can’t have both. It looks like Americans might be still underestimating China, and their policies to contain her are already beginning to backfire.
Ironically, what Bessent is doing with this tariff war is giving a boost to China’s domestic market, which is going to further grow their economic influence. Just like when the Americans attempted to cut China out of the semiconductor industry, China in turn focused on self-reliance and they are now increasingly becoming leaders in the semiconductor field.
China is capable of doing this because they have a massive manufacturing capability to begin with and an incredibly complex manufacturing ecosystem in Shenzhen, which is a much more advanced and affluent city than anything in the United States, hate to burst that bubble.

If you really want to compare strength between the U.S. and China, a better comparison is the cost of living. While its true that U.S. salary is three to four times higher, the cost of food is much lower in China, taxes are also lower, so the standard of living is higher in China.
Also, if Chinese consumers buy more and U.S. consumers buy less from the world as a result of this trade war, who has more power to influence the global economy? This is a losing strategy from Mr. Bessent and it is going to backfire on the standard of living for the average American.
But enough about China let us take a look at how this tariff war has affected the U.S. economy thus far.
Are the Tariffs Creating Higher Inflation and Loss of Jobs?
Trump has said repeatedly that tariffs are a tax on a foreign country, not the American people, “it’s a tax on a country that’s ripping us off and stealing our jobs. And it’s a tax that doesn’t affect our country. And you could see hundreds of billions of dollars of tariffs on other countries also.”
The dollar’s fall this year is the steepest since 2008. It reflects weak confidence in the US economy.

US interest rates are not going down they are flying higher. And this is bad for everyone in America. People with mortgages are going to get squeezed, business and personal loans will also get repriced upwards.
Higher interest rates are bad for the stock market and economic growth. Companies can’t expand their operations, their loan payments get more expensive, as a result salaries are also put under tremendous pressure. This creates a snowball effect where people are earning less which leads to lower consumption, in the broader economy. Major banks are already sounding the alarm, rates could go much higher. This puts the US consumer under threat which makes up about 70% of GDP.
Onshoring manufacturing is going to take years to fully manifest. And people will be hit with higher prices on goods from the world. Everything coming in from Canada, Europe, Asia, the Middle East are going to be higher in price and that’s going to be very inflationary.
There is another complication to all of this. There are three possibilities for who will have to “eat the tariffs” in a tariff war.
The tariff can be “eaten” by either the exporter to the U.S., the importer to the U.S., or the U.S. consumer. Bessent has stated his conviction numerous times that he is without a doubt that the exporter will eat the tariff in all cases, that is, with all countries. Because according to Bessent to cut out the US consumer from their trade would be suicide. And this is true for some very exposed countries.

Mexico and Vietnam are at the top of the list after China. In their case, the greater majority of their trade is with the United States so they are in a tough bind here. In the case of Vietnam, they have offered to remove their tariffs on U.S. goods. However, Peter Navarro, White House advisor on economics, reportedly said no, that the condition would have to be that they forfeit all trade relations with China.

In other words, Navarro is asking for countries to pay their pound of flesh. It is effectively asking Vietnam to remove itself from the growing massive economic hub that is occurring in Asia right now. Who in their right mind would do that? It is effectively asking nations to commit harakiri in fealty to the American Empire.
As discussed in Part I of this series, it has now been discovered that this tariffing of the world was never about the U.S. getting screwed by tariffs on U.S. goods, but rather about putting a criminal level of pressure on nations to force them to cut China out of trade with the rest of the world and sign over their key industries to the U.S. empire.
This is a situation that should not be occurring if these tariffs were applied properly as protective tariffs. It completely defeats the purpose of putting a tariff on an imported good, if the end result is that businesses and U.S. consumers have no choice but to pay higher prices for said good, it works as a revenue tax NOT a protective tariff a la McKinley.
The only option is to not purchase the good, or pay a much higher price for this good. What do you think this is going to do to small businesses and the U.S. consumer? Small businesses already have higher prices typically, since they are not as streamlined and their profit margins are smaller, so they are going to go belly-up. And U.S. consumers will either have to forego access to many goods now with these tariffs, or they will have to pay even higher prices, which is inflationary, making them even poorer.
When Beijing raised their tariff to 125% this effectively blocked out all U.S. exports into China. That’s around $150 billion worth of revenue vanishing into thin air. American companies took another hit. The U.S. crushed their own domestic demand with their 145% tariff to China and their corporate revenue in turn was hammered by China’s 125% retaliatory tariff.
China has secured their global supply chains and has the global majority as trading partners. In other words, unlike countries like Canada, Mexico and Vietnam, China didn’t just rely on U.S. trade, it saw where the wind was blowing and began diversifying its trade back in 2018. So, they are able to take this hit. Whereas countries who have failed to diversify, such as Mexico and Canada and are at the mercy of the United States as their primary trading partner. This is the lesson that the entire world is looking at right now, the U.S. is not a reliable trade partner.
But the Trump team appears to have not realised that this trade war is a double-edged sword.


So looks like prices for U.S. consumers are going to rise after all Mr. Bessent. And American workers are going to be losing jobs in the manufacturing sector.

The chart below gives you an idea of how much China alone supports U.S. jobs in manufacturing through U.S. exports to China which are now lost, likely forever. With the top exporter states being Texas, California, Louisiana, Indiana and Illinois etc. whose manufacturing industries are now left totally in the lurch over this trade war and are likely not going to be able to sustain their industries at this point.


But don’t worry guys. Trump says the tariffs aren’t going to hurt business in America…that is if you are “big business.” Why? Because big business already got massive tax cuts. You the American people are going to be footing the bill for their loss in profits over this tariff war.


Trump is transferring wealth from private households all the way up to the federal government to spend through this tariff war on the world.
[Author’s note Feb 12 , 2026: This has now been confirmed with the stats for 2025 now in.]

Trump has mused to the bottom third of America that he could possibly consider dropping taxes for this group which is just eeking by at this point. However, in reality, his tariffs on the world are taxing the bottom third of the American population the hardest.
[Author’s note Feb 12, 2026: And Trump still has put a cap on credit card interest rates at 10% like he had promised he would.]
Meanwhile small businesses who can’t survive a weeks-to-months long siege are already going belly-up in the cause for “Making America Great Again.” Plenty of American businesses are going to be destroyed by this tariff strategy. And these are small enterprises that rely on the Chinese supply chain for affordable manufacturing. We could see massive unemployment and entire local economies collapsing.
Ironically, Bessent’s tariff strategy will deindustrialise America faster than ever before. And if you think the lockdowns were brutal on small businesses, wait and see what kind of carnage we are in for as a consequence of this trade war.
Bessent’s weaponised tariffs are inflationary for US consumers, they are raising prices for American consumers and lowering their standard of living and if this continues long enough, U.S. consumption will collapse and the economy will nose dive.
Bessent said in his interview with Tucker Carlson:
“Well, I don’t know if they [China] can retaliate for a couple of reasons. If you look at the history, and I used to teach economic history, and when you look at the history, we are the debtor nation, we have the trade deficits. The surplus nation is in the weaker position because the Chinese business model and the economy are the most unbalanced, imbalanced in the history of the modern world. We’ve never seen anything like this in terms of their export level relative to their GDP, relative to their population. They’re in a deflationary recession/depression right now. They’re trying to export their way out of it and we can’t let them do that.”
Again Bessent is talking about China as some sort of deranged Frankenstein, an exporter monster, and it is up to America to save the world from Chinese….affordable and high quality goods?!?
Bessent continues: “And this is the first step towards realigning that a lot of our trading partners, including some of our allies, have not been good partners. If tariffs are so bad, why do they have them? Or, if the American consumer is going to pay all the tariff then why do they care about tariffs. Right, because they [the exporter] are going to eat them.
…
So this is a national security issue that we’re seeing here but it’s also an economic security issue and it’s to, I don’t want to say redistribute, but it is to give working Americans real wage gains and enhance their lives…Wall Street’s done great, it can continue doing well, it’s Main Street’s turn….and that is what we saw yesterday, it’s Main Street’s turn.”
Yesterday (from that interview) when there was a particularly bad day in the U.S. stock market where many Americans lost their life savings. That was apparently Main Street’s turn….
For all of Bessent’s insistence that it is “Main Street’s turn” we can now see that prices are indeed increasing, manufacturing companies are not going to be able to sustain the squeeze in profit margins for too long, unless you are one of Trump’s favourite children and are considered “big business.”
There will be a massive loss of jobs in the millions from the drop in foreign investment, in foreign employment, and foreign trade. Borrowing will be more costly in a higher interest-rate environment. Things are going to be more expensive or impossible to manufacture, with tariffs or trade bans on essential materials required to finish these manufactured goods.
Again, supply chains cannot be created overnight, this is going to take years. During this time more jobs will be lost and more small businesses will go belly-up.
As part of a means to quell the gathering mob with torches and pitchforks, the Trump team mulls over exporter tax credit as a tariff counterweight.
This is as asinine as it gets folks.
Trump and friends are considering giving U.S. companies exporter tax credits to counter-foreign retaliation. So, if Europe decides to slap an import tax, US exporters will eat some of the tariff and get U.S. government subsidies. This is funny and sad at the same time, especially when the U.S. keeps scolding the world for subsidizing their exports. Trump is now willing to do the same for his own companies. But think about how ridiculous this is. Trump wants to collect tariffs from U.S. consumers and use it to subsidize U.S. companies for retaliatory tariffs they are being charged on their exports.
At this point I have lost count of all the multiple angles that the U.S. consumer is expected to foot the bill from this brilliant plan to “Make America Great Again.”
U.S. job openings have decreased by 290,000 in one month. 7.48 million down to 7.19 million according to monthly Bureau of Labor Statistics published on April 29th, 2025.
But Bessent continues to state it is not up to the U.S. to de-escalate but China, despite the fact that it was the U.S. that started this whole thing.

[Author’s note Feb 12, 2026: The tariffs against China are not the only thing hitting the American producer and consumer hard, the high tariffs on Canadian steel and aluminum, for instance, also heavily hit the U.S. manufacturing industry this past year, among many other examples.]
No pain, no gain right? Maybe if you live on Wall Street, but this is looking like the end of Main Street.
…but I guess this is all according to the plan? After all, we are the good guys…right?

You can now read Part III here.
The Difference Between William McKinley’s American System School of Protective Tariffs and Today

You can read the First Instalment here (which focuses on Mathew Carey and Henry Clay as the founders of the American System of protectionism and their opposition to the British system of free trade), the Second Instalment here (which focuses on Lincoln and his advisor He…
Cynthia Chung is the President of the Rising Tide Foundation and author of the books “The Shaping of a World Religion” & “The Empire on Which the Black Sun Never Set,” consider supporting her work by making a donation and subscribing to her substack page Through A Glass Darkly.
Also watch for free our RTF Docu-Series “Escaping Calypso’s Island: A Journey Out of Our Green Delusion” and our CP Docu-Series “The Hidden Hand Behind UFOs”.
[1] https://www.linkedin.com/posts/jason-miller-32110325_supplychain-shipsandshipping-manufacturing-activity-7380572476654747648-BzHo/?utm_source=share&utm_medium=member_desktop&rcm=ACoAAABWRDcBg3vMfrpsxI6nCCPz-QgWQPdpCF4
[2] Ibid
[3] Ibid
[4] https://ec.europa.eu/commission/presscorner/detail/en/qanda_25_1930
[5] https://www.whitehouse.gov/fact-sheets/2025/07/fact-sheet-president-donald-j-trump-secures-unprecedented-u-s-japan-strategic-trade-and-investment-agreement/
[6] https://edition.cnn.com/2025/08/26/business/south-korea-us-investment-deal-intl-hnk
[7] https://www.legal500.com/developments/thought-leadership/new-us-vietnam-transshipment-tariff-agreement/
[8] https://www.nytimes.com/2025/08/08/business/taiwan-tariffs-chips-trump.html
[9] https://edition.cnn.com/2025/08/01/business/trump-tariffs-countries-list-vis
[10] https://ustr.gov/about-us/policy-offices/press-office/press-releases/2024/september/ustr-finalizes-action-china-tariffs-following-statutory-four-year-review
[11] https://www.bbc.com/news/articles/cwy0147vxyqo
[12] https://bbcincorp.com/offshore/articles/trump-tariffs-list
Part 3 is now published, apologies for the delay. The title is "The Difference Between William McKinley’s American System School of Protective Tariffs and Today" and you can read it here: https://cynthiachung.substack.com/p/the-difference-between-william-mckinleys
The breadth of your competence is impressive. Keep up the good work.